61% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you can afford to take the high risk of losing your money
- Experts highlight eToro UK as an innovative trading platform suitable for beginners, particularly praising its copy trading and social networking features. However, they note significant drawbacks, including high FX conversion fees and limited access to certain markets, which may deter experienced investors.
- Across 283 user reviews on Good Money Guide, averaging 3.4/5, customers appreciate the platform’s user-friendly interface and the variety of investment options available, especially in cryptocurrencies. However, some users express concerns about account management issues and high fees, indicating a mix of satisfaction and frustration with the service.
Expert rating
Our expert rating is the average of the areas listed here, each scored out of 5 by our team.Our experts have rated eToro UK across five key areas of our review framework.
- Pricing4.5
- Market Access5.0
- Online Platform4.5
- Customer Service4.5
- Research & Analysis4.5
Pros
- Really simple to use
- Social and copy-trading
- Set your own leverage
- Pre-built sector portfolios
Cons
- Can only trade and invest in USD
- No SIPPs or ISA
- No direct market access
See full expert review
Our verdict
eToro is a social trading platform that lets their users share new and existing CFD positions and their investment portfolios. eToro was founded in 2007 in Tel Aviv, Isreal and has grown to offer investing and trading on 3,000 global assets (including real cryptocurrencies) to 30 millions users worldwide.
61% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you can afford to take the high risk of losing your money
Is eToro a good broker?
Yes, eToro does have its flaws for experienced investors, but if you are just getting started eToro is a great introduction to financial markets. eToro is actually a very innovative trading platform offering copy trading, social networking and unleveraged CFDs.
eToro is one of the most innovative trading platforms with a huge range of popular investors to follow and good access to global stocks and cryptocurrency.
- Pricing: Even though eToro is commission free there are high FX conversion fees between 1.5% and 3%. Overnight financing is also expensive for CFD positions compared to competitors.
- Market Access: For the majority of investors you can trade the most popular markets, but lacks access to small-cap stocks and exotic derivatives.
- Platform & Apps: Very good, nearly gets top marks for intuitiveness, but misses out because of no sophisticated order types
- Customer Service: No phone number available to non-premium clients, but generally quick responses to chat and email queries.
- Research & Analysis: A mixed bag here – some good social investing fees on the platform and digestible guides, but no direct actionable research.
Is eToro better for trading or investing?
Ever since I sat in The Angle pub, next to the Silicon Roundabout opposite where I was a stockbroker (at Walker Cripps Weddle Beck) 15 years ago discussing the merits of eToro as a forex broker, I’ve been fascinated with their journey. I’ve interviewed the founder, the UK MD and watched (despite the industry’s loathing) as they have shrugged off the masquerade of day trading, into becoming a global investment platform sensation. In this review, I’ve tested them year after year and pontificated on what sort of customer should be using them.
In the past, I’ve been very rude about eToro, I didn’t like the way they’d gamified trading and along with Plus 500, they almost made it too easy for inexperienced traders to play the markets.
But are times changing?
Social & Copy Trading
A while ago, we published an interview with the founder of eToro Yoni Assai, about whether or not copy trading could be a challenger to traditional fund management. Copy trading is not new, it’s been around for years, whereby investors will copy the positions of an amateur trader in the hope of making money.
I first came across the concept about 15 years ago, when traders would follow futures traders on Strategy Runner. This of course was for professional regulated advisors to make it easier to have a wider client base and helped with execution allocations. The Strategy Runner technology was later bought by MF Global before its demise. Then came MT4, again, focussing on high-risk markets, like forex and index trading.
But one thing these platforms lacked was a community.
Trading Communities
This is odd because the trading and investing community is one of the most focal out there. There are some hilarious bad pontificators and some very good ones across the entire investment landscape. Seeking Alpha, has some excellent lay contributors looking at stock fundamentals. LSE.co.uk (“London South East” and absolutely no relation to the London Stock Exchange) still have a vibrant community of share chat for UK small-cap stocks. Reddit, has it’s meme’s for pump and dump schemes, and even Saxo Markets, the professional trading platform, tried to introduce a social network for traders called tradingfloor.com where you could link your trading account and see and copy other traders. Covestor tried the concept for stocks in the US, but couldn’t make it work.
One very interesting aspect of eToro’s social trading offering is that they now have a huge amount of data from a broad range of successful investors and traders. They have packed this all together into something they call the GainersQTR smart portfolio which aggregates the investments of the best popular investors on the platform.
But eToro keeps on going from strength to strength. So what is the appeal and why do they have over 20 million users and growing?
Investing for growth
The first thing eToro is keen to point out, when I spoke to the newly appointed UK MD, Dan Moczulski, is that eToro is not a trading platform anymore, they want to be an investing platform. I’ve known Dan for years, he knows the markets and the technology inside out and is well respected within the industry. So I spent an hour with Dan on Zoom, whilst he explained what eToro was all about and where they want to go.
When you execute a trade, unlike other trading platforms where max leverage is automatically given, the default leverage setting on stocks is zero, you can opt for more if you want. However, even though eToro buys the stock in the underlying market, you don’t get voting rights, can’t transfer the stock out, but you do receive your entire dividend entitlement (after it’s been taxed at source). For index and forex trading, though it reverts to form and leverage is set at 20x for indices like the FTSE and 30x for Forex pairs like EURUSD.
Day trading
eToro is not very good for day trading. For a few reaons, the main one being they don’t want to be. My mate Dan, the UK eToro MD told me that they want to be an investing platform rather than a trading platform. He was actually quite put out that we’d included eToro in the trading section, rather than the investing category.
But, whilst I still think there are better options for longer-term investors (although their copy trading track record is doing very well), I don’t think eToro is any good for day trading. There isn’t enough order functionality like, algos, DMA, OCOs, or even limit entry orders. Prices, even though they mimic the bid/offer cannot be tightened up with DMA access. Yes, there is an opportunity to take intra-day positions on indices and forex pairs, but it just doesn’t “feel” like a day trading platform to me.
Brokers like IG, CMC Markets, and City Index are much better for short-term trading. You can compare what we think are the best day trading platforms here, and see how eToro fits in.
Diversfication
But they say, that what they are actually trying to promote is diversification in portfolios by giving new investors the tools to explore the markets. One way they try and do this is through fractional shares and the way people buy stocks. They say they want to give people the opporuntiy to buy lots of little amounts of lots of different stocks (encouraging diversification), If you have £1,000 to invest, you can buy £100 of 10 shares instead of having to figure out how many shares of company A, B & C equates to £100, if at all.
Recurring orders
eToro have just introduced these and it’s been a long time coming. Being able to set up regular buy orders is a really power tool for beginner investors as it forces you to create good investing habits. One of the best ways to invest is little and often when you can afford it. So you can set up regular orders just after you get paid, which means that you are always allocating money to the market. You also benefit from reduced FX conversion fees (0.75%), which means itis actually cheaper for you to invest automatically than to do it yourself.
USD account balances
One thing though, that has always irked me about eToro and one of the reasons I’ve classified it as a trading platform rather than investing account is that all trades are settled in USD. In my mind, they fall at the first hurdle as an investment platform, because, how can you have an investing account where you don’t actually own stocks, you can’t invest in an ISA, there are no SIPPs and you are hit with dreaded foreign exchange fees on every trade you make. All those things are key to an investment account.
But, Dan was quite keen to explain why this was the case. It’s a one size fits all solution. If they want to offer free trading, they have to keep things as simple as possible and using USD as a default currency solves two issues.
One, USD is a global currency and most of the trades on the platforms would be settled in USD anyway, even in the UK.
Does zero commission equal zero costs?
The second issue is how they make money when they have zero commission. eToro makes money on foreign exchange (roughly 0.5% per trade) and they make money from withdrawal fees. There are also some stocks that are not zero commission and CFDs are exempt where eToro makes money on the bid/offer spread. Zero commission may be a loss leader of sorts in the UK, as whilst they earn 0.5% in conversion fees, they lose
As an eToro trader you used to be able to offset that FX charge, because if you ought UK shares, you were not charged stamp duty. But eToro has recently announced that they will no longer be absorbing the stamp duty tax. eToro said they absorbed this as part of their simplicity and low-cost model. But unfortunately, that is no longer the case.
Essentially, you get what you pay for and if you want all this for free you have to compromise on something, which is everything being dealt in USD.
38 Million Users
Perhaps, eToro’s most valuable asset is its client base. 38 million users, all with differing opinions and sentiment. Afterall, that’s what makes market. Opinion, it drives buy and it drives sellers. When more people buy the market goes up, and viceversa.
eToro has built a community of almost 20 million accounts, traders or investors. And when you open up the platform it definitely has more of a social media platform instead of a trading platform.
There are two types of community.
The first is the opinion-based, where the feed is populated with the latest views from eToro clients.
The second is copy trading. You can copy anyone you want (as long as their account settings permit it). Or you can copy what eToro call “Popular Investors”, these are investors who have applied to join eToro’s copytrader platform and aim to earn money from it.
Popular investors
Popular investors can earn up to 1.5% of AUC (assets under copy), or however much money other investors on the platform have chosen to allocate to copy their portfolios. However, eToro is keen to point out that once you have $15,000 copying your trades, you are vetted (not endorsed) by eToro and have to stick within risk parameters. Otherwise it would become a scammers paradise.
The thing about investing is that it’s actually quite easy, any fund manager will tell you that the key is to do your research, buy some good stocks, and then do nothing for a very long time. So as long as you do your research and pick some good investors to follow, who are following the same principle then you “should be ok”. BUT, fund managers have oversight, they have compliance officers and risk committees, so they can’t just change their mind about how and what they invest in. Of course, with some notable exceptions, cough, cough Woodford.
When you look at a potential trader to copy, you can see their trading history, their risk parameters and also what they are invested in. Which if nothing else is a good place to start building a portfolio, because you can see where the best performing investors are putting their money. Which is actually a good strategy in the fund management world as well. Morningstar for instance shows the top ten holdings a fund holds. Take a look at Blue Whale for example, you can see what they are invested in and either copy them by buying the fund, or just buy the top ten stocks they hold in your own investment account. If you want to know how fund managers actually invest we have a couple of good interviews with Stephen Yui from Blue Whale and Jamie Ross from Henderson.
If you don’t know which unregulated amateur traders to follow, you have the option to buy a portfolio of aggregated “Popular Investors” diversifying your risk further, or can opt for a smart portfolio that has been put together by a professional investment firm.
Or if you want exposure to sectors there are Thematic funds, like, for instance, if you want to invest in the Metaverse, which is a hot topic right now. eToro have a selection of what they call Smart Portfolios, where they have selected stocks relevant to sectors, a bit like buying ETFs. So if you want to invest in the Metaverse, but don’t know where to start the MetaverseLife Smart Portfolio contains a basket of stocks and crypto that has exposure to the Metaverse.
Cryptocurrency
This brings me quite nicely onto Cryptocurrencies. In the UK Crypto derivatives are banned by the FCA for retail traders. If you want to invest in cryptocurrency in the UK you either have to be classified as a professional trader, or by them on a crypto-exchange or platform like eToro on a fully paid-up basis.
One thing eToro has always been really good at is being first to market with new assets, they offer quite a wide variety of cryptos compared to other regulated fintechs, but also vet which cryptos they add by demand, liquidity, the tech behind them and also overall due diligence. Cryptocurrencies are too big to ignore and accounted for roughly 73% of eToro’s commission during the second half of 2021. So you can’t trade crypto derivatives, but you can invest in them with eToro, you can buy them, sell them and transfer them out to an external wallet with eToro money.
Customer Service
If you are one of the masses, customer service can be a bit of a pain, there is no telephone helpline and the support enquiries that we have made have generally taken a day or so to be responded to.
But with 20 million customers, a great proportion, who are no doubt beginners that is no surprise. If you have enough money on account ($25k upwards), you do get access to a dedicated desk of dealers in Europe and Canary Wharf.
So, who is eToro for?
So if you are a small trader, eToro does offer a very innovative way to access the financial markets. It’s quite jolly on the social media feed on the platform, and it is what it is. This is what people want, obviously, as they have 20 million customers. The largest incumbents still have only hundreds of thousands in the UK and in the US a few million.
The key difference between investing in trading, is that investing is a long-term thing, trading is speculation for short-term profits.
However, even though eToro may be positioning itself as an investment platform rather than a trading platform, I’d still consider the investments on offer to be high risk, for your fun money.
I genuinely enjoyed playing with the platform and testing what was on offer. It’s game-changing, but I still think they have a long way to go before you’d allocate more than a small percentage of your overall investment portfolio with them. Your longer-term investments are in my view better off with a boring investment platform like Hargreaves Lansdown or Interactive Investors. But, it will be interesting to see how eToro matures over the years, along with their customer base.
Is eToro a good trading platform?
Yes, eToro is a trading platform where you can trade CFDs (Contracts for Difference). It is also an investing platform where you can buy shares and ETFs as an investment.
What are financial instruments on eToro?
Financial instruments refer to the markets or stocks you can trade. With eToro you can trade around 3,00 stocks, 75 cryptocurrencies, 27 commodities 39 currencies, 19 indices and 264 ETFs. Data correct Oct 22
What is copy trading on eToro?
Copy trading means that you automatically copy the trades of other investors on eToro. It is a type of passive investment strategy, but is risky because you are putting your investing decisions in the hands-on an unregulated amateur trader.
How much does it cost to open an eToro trading account?
It is free to open a trading account with eToro but if you want to start trading, you need to deposit funds. In the UK the minimum deposit starts from $50 USD and varies across the countries.
Does eToro have a mobile app?
Yes, a huge amount of trading and investing is done through eToro’s mobile apps. The app is available in both the Apple and Android app stores. You can compare eToro’s app to some of the best trading apps here.
Does eToro offer CFD trading?
Yes, you can trade CFDs with eToro, but you must understand how CFDs work because they are leveraged trading products which means that you can lose money quickly when trading CFDs.
Is eToro the best CFD broker?
No, only around 5% of eToro’s trading volumes in 2021 were from CFD trading, the rest was from cryptocurrency and investing. Whilst eToro does offer CFD trading their offering is very light compared to brokers like Saxo Markets and Interactive Brokers which both offer direct market access (DMA) CFDs.
Can you upgrade to a professional client with eToro?
Yes, you can upgrade to professional client status with eToro. You will get less protection from the FCA, but you will get better margin rates if you want to increase your trading leverage. However, the majority of customers on eToro are private clients in the UK are classified as retail clients. It means they are non-professional traders and investors and as such get more protection from the FCA and reduced leverage rates. You can compare the difference between retail and professional traders here.
Is there a risk of losing money with eToro?
Yes. As with all investing and trading accounts, you can lose money. There is a high risk of losing money when trading with eToro as only around 20% of retail traders make money when trading CFDs. The risk of losing money is less when investing, as you are not trading on margin. But as with all investing if you pick poorly performing investments or copy traders who perform badly, you will lose money.
If you cannot afford to risk losing money and you are thinking of trading on eToro you should not do it. eToro is a trading and investing platform and it is a well-known fact that around 80% of traders lose money on CFDs. Even with investing, your money is at risk, and if you invest in stocks and markets that go down you will get less back than you put into your eToro account. However, eToro does have a growing copy trading platform where you can see the portfolios of profitable traders and investors.
Are eToro fees high?
eToro fees are not high for trading as they offer commission-free trading. However, if you are trading CFDs with eToro, the overnight CFD financing charges are much higher than other brokers. FX fees are also relaively high when buying US stocks and converting GBP to USD.
Is your money safe with eToro?
In the UK eToro is regulated by the FCA so if they go bust your money (up to £85k) is protected by the FSCS. However, your money is not safe from you making bad investment decisions or picking a bad trader to copy trade.
Does it cost money to withdraw funds from eToro?
Yes. eToro charges $5 when you withdraw money. This is one way that eToro makes money.
Do I have to pay tax on profits made with eToro?
Yes. If you make money with eToro you have to pay tax on the profits. The only way to avoid paying tax on trading profits is to trade financial spread bets in the UK. If you want to know more about spread betting, I explain why it is tax-free investing here.
Does eToro have a monthly fee
Yes. eToro will charge you $10 a month if you do not use your account after 12 months. This is called an inactivity fee and will not take you below a zero account balance.
Does eToro offer SIPPs and ISAs?
No. eToro does not offer tax-efficient stocks and shares ISA accounts of SIPPs for you to invest for your retirement. However, eToro does have a partnership with MoneyFarm where you can have a stocks and shares ISA account.
How does eToro make money?
eToro makes money on the difference between the bid and offer spread when you buy and sell shares, indices, commodities, forex pairs and cryptocurrency. eToro also makes money in fees for depositing and withdrawing money and on FX conversions.
Customer reviews
Customer ratings come from reviews left on this site. Every review is read and approved before it is published.Based on 283 reviews
- Excellent20%
- Very good25%
- Basic35%
- Poor12%
- Bad7%
Read customer reviews
Trusted
They make investing easy and understandable.
convenient
ease of use, choice of products
Love everything
I’ve been using Etoro since Covid. I have a diamond account. There’s a dedicated account manager giving constant updates, educational content, networking sporting sessions like watching F1 and Liverpool match at National Stadium. The user interface is the most intuitive and best across all the platforms I have seen.
Best Investment Partner
It’s best investment platform for investments in all areas , stick to cryptocurrency, also feature of interest on cash balance is also worth noting
Nice and easy to use
Very good for the beginners. Etoro has improved his service along the time. 3 years I use Etoro, and satisfied.
EToro is best.
Interactive broker does not provide us the possibility to deposit money using the debit or credit card. So sending the money to their account cost me about AED 100. Same is the issue with Saxo Bank.
Unethical and Untrustworthy Platform – Avoid eToro!
I had an absolutely terrible experience with eToro. Without my consent, they closed my account while I still had cryptocurrencies purchased and open. This is unacceptable. Despite multiple attempts to contact their customer service, my requests were completely ignored. No proper explanation, no support, and no resolution.
As a result, I lost my money. It feels like there is no way to get proper attention or accountability from this platform. The lack of transparency and disregard for customers is shocking.
I strongly advise anyone considering eToro to think twice. A platform that can shut down accounts without consent and ignore customer complaints cannot be trusted. If you value your investments and want peace of mind, stay away from eToro.
4 stars for its reliable platform
I just wanted to drop my two cents on eToro. I’ve been using this platform for a while now and honestly, it’s been a blast. The interface is slick, trades go fast, and I’ve made some solid moves. Every trade feels like a mini victory, and the community vibe is on point. Sure, there are ups and downs, but that’s all part of the game. What really stands out is how eToro keeps it real with transparent info and easy-to-follow charts. I even checked out Wikitoro, which serves as a neat resource of insights on eToro, and it only boosted my confidence. It’s like having a buddy with all the inside scoop. So if you’re keen on trading with style and simplicity, eToro might just be your next go-to. Cheers! Highly recommended for anyone wanting smart trading indeed.
e Toro? TORO,TORO…
Always there if I need them.
Made to pick your pocket
Every aspect of the platform aims to tell you could potentially make money fast. But that’s not how good investing strategies work.
Leave a review
eToro Alternatives
| Name | Logo | GMG Rating | Customer Reviews | GIA Annual Fees | Dealing Commission | CTA | Tag | Feature | Expand |
|---|---|---|---|---|---|---|---|---|---|
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees £0 |
Dealing Commission £0 |
See Offer Capital at risk |
Featured |
Features:
|
*Get up to £300 in bonus shares when you invest at least £300. Use Code WELCOME300. T&Cs apply.
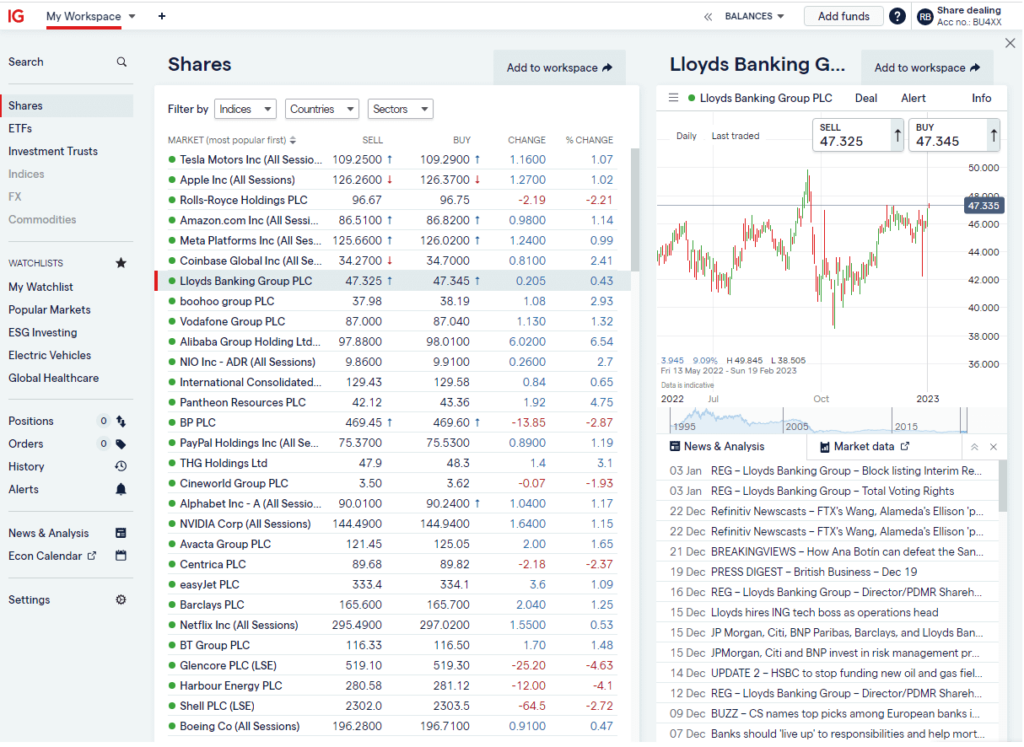
 Visit IG(opens in a new tab) Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% of retail investor accounts lose money when trading spread bets and CFDs with this provider. You should consider whether you understand how spread bets and CFDs work, and whether you can afford to take the high risk of losing your money. Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.5.0Excellent Our experts have rated Is IG's GIA A Good General Investment Account? across five key areas of our review framework.
Pros
Cons
See full expert reviewOur verdictIG is primarily a trading platform (and one of the best, at that) but also has an investment account through which you can deal in physical stocks and shares, including ETFs, in the UK, Europe, US and Asian markets. If you don’t want to choose your own stocks, IG also has a managed investment product called Smart Portfolios. These are pre-made diverse portfolios with exposure to the global markets through shares, bonds, property and commodities. IG is a good choice for traders also looking for a cost-effective way to hold long-term investments in a GIA, or a stocks and shares ISA or SIPP. Capital is at risk. Is IG's GIA a Good Account?Yes, we rank IG as one of the best combined investing and trading platforms in the UK. You can invest with IG through a GIA, ISA or SIPP in either individual stocks or through pre-made Smart Portfolios. Pricing: Very good, IG has recently removed their account charge and there is no commission when buying and selling investments. If you are buying US stocks there is an FX fee of 0.7%, which is quite high compared to peers. Customer Service: Despite it’s size, IG has very good customer service. You can still buy and sell shares over the phone with a real human being. The majority of issues can be solved through their webchat function or WhatsApp customer service number. Research & Analysis: IG excel at added value. The platform has integrated technical signals, news feeds, fundamental data and the IG social channels have a neverending flow of market analysis. The IG podcast, “The Art of Investing” was also voted Best Financial Podcast in the 2026 Good Money Guide Awards. Market Access: Excellent – you can invest in over 12,000 stocks, funds, investment trusts and ETFs (including small caps). One letdown, though, is the lack of access to funds and bonds – you’ll be better served by a traditional stockbroker like Hargreaves Lansdown. And unlike some rivals, like Bestinvest, IG can’t provide advice on investments. App & Platform: What is IG’s Platform Like to Use? IG’s investment platform is the same as its trading interface so this will be familiar to its short-term speculators. The platform offers good visuals of investments, with associated news and analysis.
|
|
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees £59.88 |
Dealing Commission £3.99 |
See Offer Capital at risk |
Features:
|
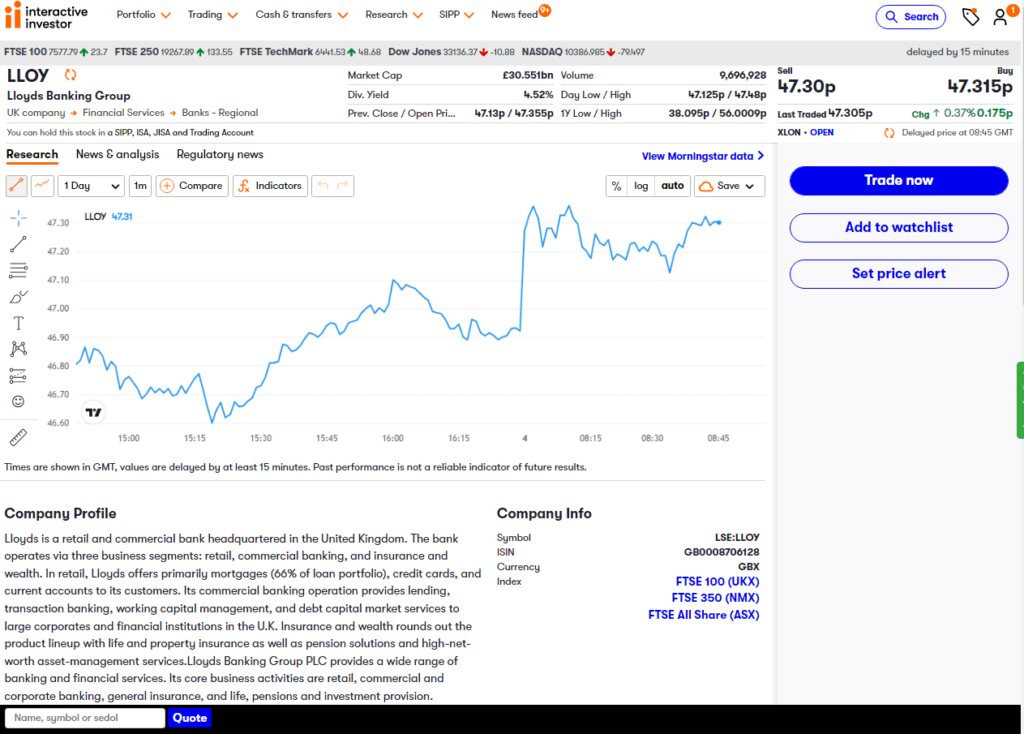
 Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.4.8Excellent Our experts have rated interactive investor General Investing Account across five key areas of our review framework.
Pros
Cons
See full expert reviewOur verdictThe interactive investor (ii) GIA is an all-rounder with an attractive fixed fee pricing model. There’s access to a wide range of markets including UK and international shares, bonds and ETFs. Capital is at risk. Is Interactive Investor a good general investing account?Yes, ii’s GIA won our award for best general investment account in 2023 and 2022. This is because of its excellent fixed-fee pricing, which makes it a good choice for investors with over £10,000 to invest. ii’s fixed fee keeps your total account costs low no matter how big your portfolio gets. You can also invest in markets ranging from UK and international shares to funds, trusts, bonds and ETFs. Fees A GIA with ii costs from £5.99 a month if you have less than £100,000 in your portfolio on their core plan, above that the monthly cost rises to £14.99 on the ii plus plan. Included in both are a free stocks and shares ISA account and SIPP (for pension investing). Individual share deals are £3.99 per trade. It’s a little cheaper to buy funds on the Plus plan at £1.49 per fund buy or sell. If you are buying international shares, it’s quite expensive compared to other providers like IG or Freetrade, who generally offer international share dealing for free. Especially when you take into account that FX fees for converting GBP to USD are 0.75%. Is ii’s GIA Better than its ISA? The GIA is better if you have lots of money to invest as the maximum you can put in an ISA tax-free each year is £20,000, so anything above that you should invest in a GIA. However, if you have less than £20,000 to invest each year, the ii ISA is a better option as your profits will be tax-free. What is ii’s Platform Like to Use? ii’s platform is very easy to use and it gives lots of market data on potential investments.
|
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0% |
Dealing Commission £1 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
See full expert reviewOur verdictLightyear is one of the better free investing apps as it provides access to US stocks and local markets with FX fees as low as 0.1%. Lightyear is a new investment app that offers low cost investing in UK, European and US shares. The company was founded by one of the first Wise (Transferwise) employees, Martin Sokk with a similar objective of making investing as cheap and easy as possible. Is Lightyear Good for Investing?Lightyear was voted best investing app in the 2026 Good Money Guide Awards and is a simple and approachable way to invest in stocks and ETFs without unnecessarily large fees. A very well-designed low-cost investing app with discounted FX charges, limit and recurring orders for investing in local and international markets. Special Offer: Sign up with the code GOODMONEYGUIDE to get up to £100 in fractional share to your GIA. Capital at risk. – – Terms apply: https://lightyear.com/en-gb/signup-promotion-terms. You must be a new user and deposit at least £100 within the first 15 days after signing up. The reward can be withdrawn 6 months after it’s credited. Fees: Lightyear is cheap for investing. The GIA has no account fee and charges only £1 commission for UK trades and up to $1 for US stocks but free for trading ETFs. If you are investing in a stocks and shares ISA, there is no commission on buying and selling stocks and shares. Much like the founders’ alma mater, Lightyear makes its money from FX fees which it adds to the interbank rate, so conversion costs are transparent. When I interviewed Martin Sokk, he told me Lightyear planned to expand internationally fast so that its users could invest in both their local and the US markets, since many people want to invest in US stocks. And rightly so: US shares are all household names, and one of the key drivers for investing is to buy companies you love and use. Lightyear will make money charging 0.1% per trade (or $1, whichever is bigger) and converting GBP, HUF & Euros, etc. into USD when people buy US stocks. Lightyear charges 0.1% for converting money into USD and EUR, which is higher than Interactive Brokers’ 0.03% but much lower than the 0.5% charged by AJ Bell, Saxo Markets and IG, or the 1% from Hargreaves Lansdown and Interactive Investor. FX must be a key part of Lightyear’s monetisation strategy: if you charge very low commission and account fees, you have to make money somehow. So Lightyear aims to make its money in the background, initially from foreign exchange fees. FX is a good way to make money because a) no-one really understands how the pricing works and b) you don’t see the charge, it’s built into the buy/sell spread. You can see in the example below what the fees were when I bought some Tesla shares while testing the app for this Lightyear review. Quite a nice touch is that you get the option of making purchases repeat orders, a great way to build good investing habits. Just by investing small amounts each month, the genius of compounding returns will help you build a larger portfolio over time. Check it out with our investing returns calculator. Market Access: Lightyear constantly adds new instruments, bringing the total up to almost 6,500. These include well-known UK names such as Rolls-Royce, easyJet and IAG; to defence ETFs, US stocks. This is great because one of my concerns about new investing apps is that they normally just cater to the most heavily traded stocks, which means they are not great for more adventurous investors. It’s great to see Lightyear providing wider market access. Plus, it’s proactive. Lightyear says it has put live 98% of non-complex US instruments asked for by customers in just 3 months. One of the other really cool things about Lightyear is that you can listen to earnings calls directly on the app. As well as being able to buy fractional US shares, ETFs though limit orders and regular investing, you can also quickly see which shares pay the highest dividends or make the most money relative to their share price to help you pick stocks. Multicurrency account & order types Another point to make here is that you also get a multi-currency account, where you can hold foreign currency. The advantage of this is that you don’t need to do as many FX conversions which can help keep costs down. Related guide: Compare FX rates for buying US stocks from the UK. Progression to servicing local customers and local markets When Lightyear first started, you could only invest in a handful of UK stocks, and they were ADRs listed in the US denominated in USD, rather than the local listings on the LSE. So, you were paying an FX fee when you really shouldn’t have to. Admittedly, there is no stamp duty so technically paying 0.1% on FX rather than 0.5% to HMRC is cheaper. Lightyear has a cash (money market fund) and investment ISA, but no SIPP account, but I suspect that is next on the “product roadmap”. Are your investment safe with Lightyear? Yes, it’s safe to invest with Lightyear. Lightyear U.K Ltd is authorised and regulated by the Financial Conduct Authority (FRN 987226). Lightyear is protected by the Financial Services Compensation Scheme (FSCS). FSCS protection applies to client money only where held with banks, not where held in QMMFs. In the unlikely event of anything happening to Lightyear, there’s no way for creditors to get hold of the investments or cash that customers hold with us. Keep in mind, though, that your investments are not safe from losing money with Lightyear. Overall, the market generally goes up, but there are peaks and troughs along the way. Like Transferwise, like Lightyear To draw on one final Transferwise comparison, it is very easy to use app-as-a-tool to help you start investing as cheaply as possible. The thing is though is that, transferring money is like car insurance. No-one really has any loyalty to their insurer, they just do it and move on. Investing is different. Investing is not like insurance, when you open an investing account, you could be using it for the next 30 years. I think there will always be a place for traditional investment platforms because they provide excellent customer service and brand loyalty, they are mature platforms for mature investors and fees will eventually come down, as they have done in the past. Same as with Simpsons Tavern, it may not be as good for you as veganism, but if it survives, people will continue to go because they like it. But, if low-cost investing apps are a gateway to getting more people to invest for their future, then they are the future too and will hopefully mature along with their customers, and Lightyear, in particular, is a great place to get started. Customer reviewsCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.9Excellent Based on 676 reviews
Read customer reviewsTrustworthyThey are innovative, easy to use from youngsters to seniors. It is simply for all people! excellentsimple fast, cheapthey have an amazing UI, the platform is super fastm the fees are low and tax compliance is SUPER easy. Flexibly diverseProvides a an extended assortment of commodity types, and an easy way to track and manage profits & losses visually. QualityIt’s an easy to use application, where everything is available what you need. Not too complex, because of this everyone can use it EaseEasy to use, great tips on investment options and the new investment plans. easy to useupdate , info, Clean UIProvides clean and intuitive user interface. It is reliable and works really smooth. convenientEasy and understandable to use, ever growing features inside app. Intuitive.Product, pricing, customer support. Leave a review |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0% – 0.75% |
Dealing Commission £3.95 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
See full expert reviewOur verdictMoneyfarm is a digital wealth manager that aims to make personal investing simple and accessible. It was launched initially in Italy in 2012 by Italian bankers Paolo Galvani and Giovanni Dapra and entered the UK in 2016 and has big-name financial backers such as Allianz Global Investors, Cabot Square Capital, United Ventures and Poste Italiane. Is Moneyfarm any good for wealth management?Yes, Moneyfarm is more of a digital wealth manager rather than a robo-advisor as the portfolios are put together by investment managers, rather than automatically. The automation, as it were, is fine-tuning your portfolio to match your risk/reward choices. Unlike with other robo-advisors, with Moneyfarm you can also top up your portfolio with individual shares and ETFs. Fees: Moneyfarm charges 0.75% to 0.6% up to £100k then 0.45% to 0.35% over £100k. Moneyfarm investing account fees are scaled between 0.75% for accounts between £500 and £50,000, then above £100k are 0.45% to 0.35%. Average investment fund fees are 0.2% and the average market spread when buying and selling is 0.10%. Market Access: You can invest in 7 pre-made portfolios, but also (unlike a lot of other digital wealth managers and robo-adviors) also buy individual shares, ETFs, bonds and mutual funds online. It’s a bit of a shame you can’t buy US stocks, But Moneyfarm is best really for setting up regular investments in a GIA, ISA or SIPP, then letting them grow over time without too much tinkering and speculating on Tech stocks. App & Platform: It’s really easy to use, plus it puts you through your paces to make sure you understand what you are investing in. Apparently, my Moneyfarm investor profile is “pioneering”, which means I want to take on more risk for potentially better returns. Customer Service: This is mostly online as you’d expect but solves all issues – I’ve had some good calls with Moneyfarm about how its products work over the years, and its people really know their stuff. If you want to find out more about the ethos, you can read my interview with the CEO Giovanni Daprà on how they are so much more than a robo-advisor. Research & Analysis: Not much to speak of other than a few guides, but that’s ok, as I don’t really want Moneyfarm spamming me with stock trading ideas.
Customer reviewsCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.3Very good Based on 248 reviews
Read customer reviewsIncompetent, dishonest, do not trustIt gets better… So, after they couldn’t transfer money of mine into the right account, which cost me £15k… they didn’t accept responsibility at first, then accepted it was their error. Offered a few hundred quid as compensation, which I obviously declined and then I’ve had 15 back and forth emails with the team and no actual explanation of why it happened and why they won’t put it right for me. I’m a bit suspicious as to why they can’t work out what the right thing to do is here. So I made a Subject Access Request so that I could understand the chain of events. Obviously they’ve subsequently managed to not meet the deadline for my Subject Access Request because it’s “complicated”. This business is incompetent. They give me absolutely no confidence that this is something they’ll make right. CowboysHave come back with another assessment of my case recently. Case background – they were unable to simply transfer my funds to a pension account. They had a week to move the funds and I called every day to make sure it was fine. They reassured me it was ok and would happen. It didn’t happen… Has subsequently cost me £15k of tax relief. They have admitted it was their fault, but their “final” compensation offer has come in at a meagre £1,500. Having to go down the legal route as nobody there wants to accept responsibility for their mistake. Absolute disgrace of an operation. Do not trust them with your money. Just appallingStill refusing to pay me the money that they cost me. I lost £15k in tax relief purely because they couldn’t work out how to transfer money from one account to another. I called several times to make sure they could do it. I was reassured every time. Somehow they messed it up and then told me it was my fault. Appalling customer service. Do not seem to care that they are incompetent. I have the call recordings if anyone is interested lol Awful company. Cost me money and wouldn’t accept responsibilityMessed up the transfer of my pension funds. Then blamed me for not simply being able to allocate it into my pension account. Offered £500 as compensation when their incompetence cost me £15k in tax relief. Their error has cost me £15k and they won’t acknowledge it. I’ve lost out massively due to the company and the customer service is dreadful. Do not trust this company. Absolute disgrace. Do not trust themWorst company I’ve ever dealt with. Messed up the transfer of my funds. Subsequently blamed me for not simply being able to allocate it into my pension account. Took weeks to “review” the situation. Offered £500 as compensation when their incompetence cost me £15k in tax relief. Tried to say I should transfer more capital in the next tax year to achieve a “similar position” when that is not the case. Their error has cost me £15k and they won’t acknowledge it. I’ve lost out massively due to the company and the customer service I’ve received since is one of the worst I’ve ever experienced. Do not trust this company. Do not trust their people. They will not do the right thing when things go wrong. Very disappointed. A Rabble of ThievesAfter receiving my £10,000 into a Stocks and Shares ISA, they then proceeded to close the account and refuse to return the money. The financial Ombudsman is now having to get involved. Liars, cheats, frauds. Despicable company that must be avoided. Awful company that shirks responsibility when they've made errorsDreadful business. Messed up transferring my money into a pension account and has since offered me a pathetic £200 in compensation for the several thousands (>£10k) that it has cost me. Technology clearly doesn’t work. Despite speaking to their team about 5/6 times they still were unable to allocate my funds to my pension on time. Have since blamed the error on not being able to “automatically allocate” money into the fund despite me speaking to them several times before the end of the tax year and knowing exactly what I wanted to achieve. Hiding behind pathetic excuses and not interested in making this right for a customer. It would be refreshing if they would hold up their hands when a clear error has been made, but instead they would rather push the financial loss onto me. Dreadful business to deal with. Misleading Interest Rate on Cash ISA and Bad Customer ServiceI have just transferred a Cash ISA over to Moneyfarm from Zopa, due to better interest rates. The transfer went smoothly, however the value of the ISA has decreased, even though the interest rate is currently quoted as 4.33%. I’m no financial wizard, but by my reckoning the value should be going up, rather than down. The ‘Chat to Us’ section was of no help and my email to customer services went unanswered. Very disappointed! I will be moving my Cash ISA somewhere else before it disappears completely. Zopa we’re far better by comparison and their website was, in my opinion, more user friendly. ExcellentConsistently good performance ProfessionalPretty much “outstanding” , easy to contact, smart folk at the other end of the phone along with great financial returns – simple as. Leave a review |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0% – 0.25% |
Dealing Commission £3.50 – £5 |
See Offer Capital at risk |
Features:
|
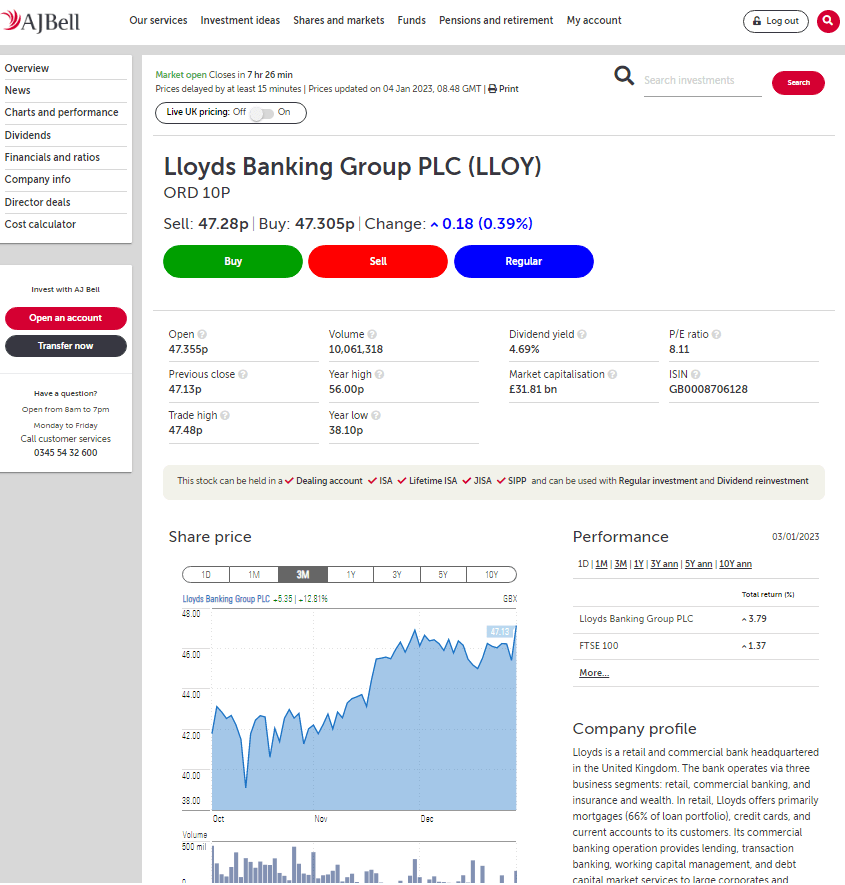
 Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.5.0Excellent Our experts have rated AJ Bell General Investing Account across one key area of our review framework.
Pros
Cons
See full expert reviewOur verdictAJ Bell’s GIA offers share dealing in 24 stock markets, bonds, ETFs and over 4,000 funds including a range created by its own team. The platform will suit those who are looking for low-cost investing when growing a small portfolio. Capital is at risk. Is AJ Bell's GIA a Good Account?Yes, AJ Bell’s GIA is one of the safest and cheapest ways to invest – outside your tax-free allowances in SIPPs & ISAs – for longer-term investors in the UK. AJ Bell won our award for Best Investing Account 2024 due to its excellent market access, low costs and customer service scores in our annual survey. Fees: AJ Bell charges 0.25% of the value of your investments for a general investment account, but share account fees are capped at £3.50 a month. Dealing costs are £1.50 for funds and £5 for shares but drop to £3.50 where there were 10 or more online share deals in the previous month. AS of May 2026, there is no commission charged for recurring investments. Market Access: AJ Bell’s GIA is most suited to investors who want the cheapest overall investment platform for starting to grow a small investment portfolio. It offers share dealing in over 24 stock markets, bonds, ETFs and over 4,000 funds (of which around 400 are investment trusts), including a range of the company’s own funds that have been created in-house so you can invest by how much risk you want to take, or by theme or region. App & Platform: Both apps and web version are really simple to use, no complaints. Customer Service: Top notch, you can actually phone someone up to ask a question. Research & Analysis: As well as being a super easy platform for beginners AJ Bell is also a serious platform for serious investors and this in reflected in the quality of their research. There are some really in-depth reports on funds and shares, plus you get a free subscription to Shares Magazine worth £220 a year by maintaining a balance of £4,000 or more across your AJ Bell investing accounts. What is AJ Bell’s Platform Like to Use? AJ Bell’s investment platform is functional and well laid out. Key share and fund information is available to view at the time of execution.
Customer reviews for AJ BellCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.2Very good Based on 1,103 reviews
Read customer reviewsGoodGood relativelyRelatively user-friendly investment app. Still very confusing and tricky to use, for me at least ReliableI trust AJBell to look after my pension fund and do what is best for me. They are responsive and thoroughly professional at all times HelpfulGreat anti fraud procedures saved me losing money to an impersonator. SimpleReally good company who have transparent fees and have a really friendly client app to trade on. Feel my retirement funds are in good hands improvinggood website, app needs to catch up EffortlessMakes investing simple and quick. TrustedThey dont do the hard sell. They provide you with information to guide you to your investing choice ReliableEasy to use platform Greateasy to use app and strong customer service |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0% – 0.45% |
Dealing Commission £5.95 – £11.95 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.5.0Excellent Our experts have rated Hargreaves Lansdown General Investment Account across one key area of our review framework.
Pros
Cons
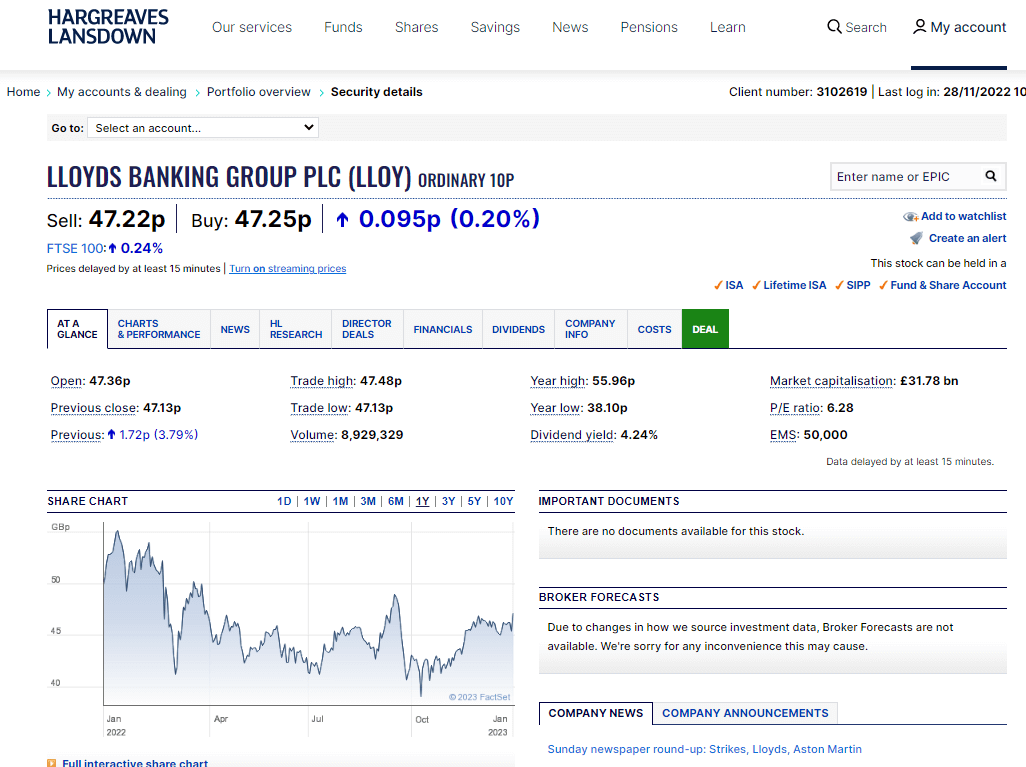
See full expert reviewOur verdictHargreaves Lansdown (HL) has plenty of account types including a GIA and several types of ISA, plus an excellent research portal. There’s access to thousands of UK and international shares, funds, ETFs, investment trusts and corporate bonds. Capital is at risk. Is HL's GIA a Good Account?HL is good for investors looking for more than just somewhere to buy and sell shares. The platform offers the most account types of all the investment platforms we compare, including a GIA, stocks and shares ISAs, lifetime ISAs, and junior ISAs. Plus, it has one of the best research portals to help you choose your own investments. And it boasts some of the widest market coverage, including thousands of UK and international shares, over 3,000 funds, ETFs, investment trusts, and corporate bonds. Fees There is no account charge for shares in a GIA with HL. Funds are charged at 0.45% for the first £250,000. There’s no charge for buying funds, but shares are charged at £11.95 per deal or £5.95 if you do over 20 deals per month. Is HL’s GIA Better than its ISA? It makes sense to open a GIA only after you have exhausted your ISA allowance. With the GIA from HL, you can invest as much as you like but with an ISA you’re limited to £20,000 a year in the tax-free wrapper. What is HL’s Platform Like to Use? HL’s investment platform is one of the best around. HL provides a huge amount of technical and fundamental data to help you choose investments.
Customer reviews for Hargreaves LansdownCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.3.8Basic Based on 1,775 reviews
Read customer reviewshideous experiencejust speechless! I created the kids accounts. They changed the primary person on my child’s account without telling either parent, locked me out when I Phoned about a login issue, then dictated what I do in my own home and with whom. Never had an experience like that! WebsiteExcellent platform for stocks, shares and cash investing. ClassAmazing customer service EfficientVery simple app. Brilliant customer service. Good range of ETFs, which I use for long-term investing. Brilliant Cash ISA also, with great interest rate. Trusted and credible. I trust my money is in a safe place. GoodCommunication IntuitiveGood, intuitive app. Very responsive customer service. ExcellentEasy platform to use ConfidenceEasy to use platform, very supportive and excellent telephone service. fantasticThey listen then execute the right strategy AccessibleEasy to use and patient/friendly when contacted. 5he brand provides access at all investment skill and money levels. |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0.15% |
Dealing Commission £0 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
See full expert reviewOur verdictDodl is a low-cost investment app provided by AJ Bell. The app fees are lower than AJ Bells, and they cater to newer investors by offering commission-free investing in AJ Bell funds, themed investments and a small selection of main market shares. Is Dodl a good investing app?Customer reviewsCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.5Excellent Based on 38 reviews
Read customer reviewsgood value investment platformGood value and simple to use, quite limited shares choices though. ExcellentStraightforward to use and a great app. Made my start into the world of investing very easy. Thanks Best interest on LISAGreat for beginners, amazing customer service and I’m getting the best interest possible on my LISA. Excellent for low cost trading….Excellent for low cost trading. Wish it had a web view So far so goodSo far so good OK not used muchOK not used much Very goodVery good Very informative, easy to use…Very informative, easy to use & friendly 5/5Great value and very user…Great value and very user friendly – aimed at younger investors and great for thid Leave a review |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees £0 |
Dealing Commission £0 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
See full expert reviewOur verdictThe GIA from CMC Invest lets you invest in major UK shares, US stocks and ETFs without having to pay commission when you deal. The app is free to use when investing in a general investment account with the Core plan. But you can upgrade to a Plus account which includes a flexible stocks and shares ISA, access to UK mid-cap shares and a USD wallet. There’s also a Premium option that gives you access to a SIPP. CMC Invest cut the fees for Plus and Premium in 2025. Is the CMC Invest General Investment Account Any Good?If you are just starting out investing, then CMC Invest is a good general investment account (GIA) for some longer-term investments. But, if you are an established and experienced CMC Markets customer you may find the CMC Invest offering too basic. Better options for sophisticated investors would be Saxo, or Interactive Brokers. Investments: Shares & ETFs Minimum deposit: £0 Account types: GIA, ISA Account charge: £0 – £10.99 per month (Premium previously £25 a month) Dealing fee: £0 Fees: General investment accounts are commission and fee free. ISA accounts cost from £6.99 a month and are included in the Plus plan. For US shares there is a conversion fee of 0.39%-0.99% depending on your account. Investing Platform: CMC Invest’s app gives you access to major stocks, and has a screener to help search for potential investments.
Customer reviews for CMC MarketsCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.2Very good Based on 237 reviews
Read customer reviewsexcellent companyEverything, from data sharing to information sharing to ideas to trade. Really good provider. I love it. Let not mobile app close it selfYou can close all your positions at one — one click ExcellenteCustomer service Extremely efficientExcellent trading platform EfficientTight spreads CustomaryAvailable anytime you need assistance, their educational videos are explanatory trustworthymarket price action accuracy and response, good spreads, very easy to use, quick withdraw and depositing easyMakes trading easy GoodEverything, good customer facing service . transparentvery easy to use interface, most competitive spreads also on futures |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees 0.6% |
Dealing Commission £0 |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.4.5Excellent Our experts have rated Wealthify General Investing Account across five key areas of our review framework.
Pros
Cons
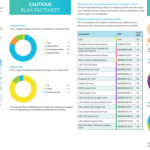
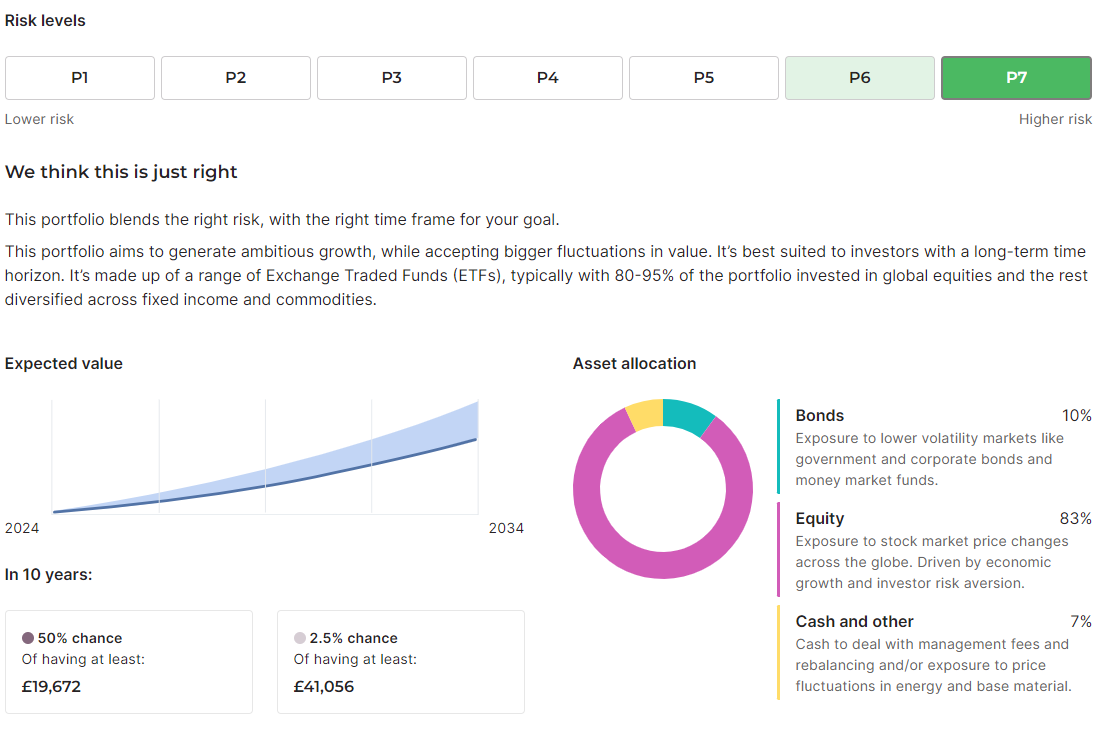
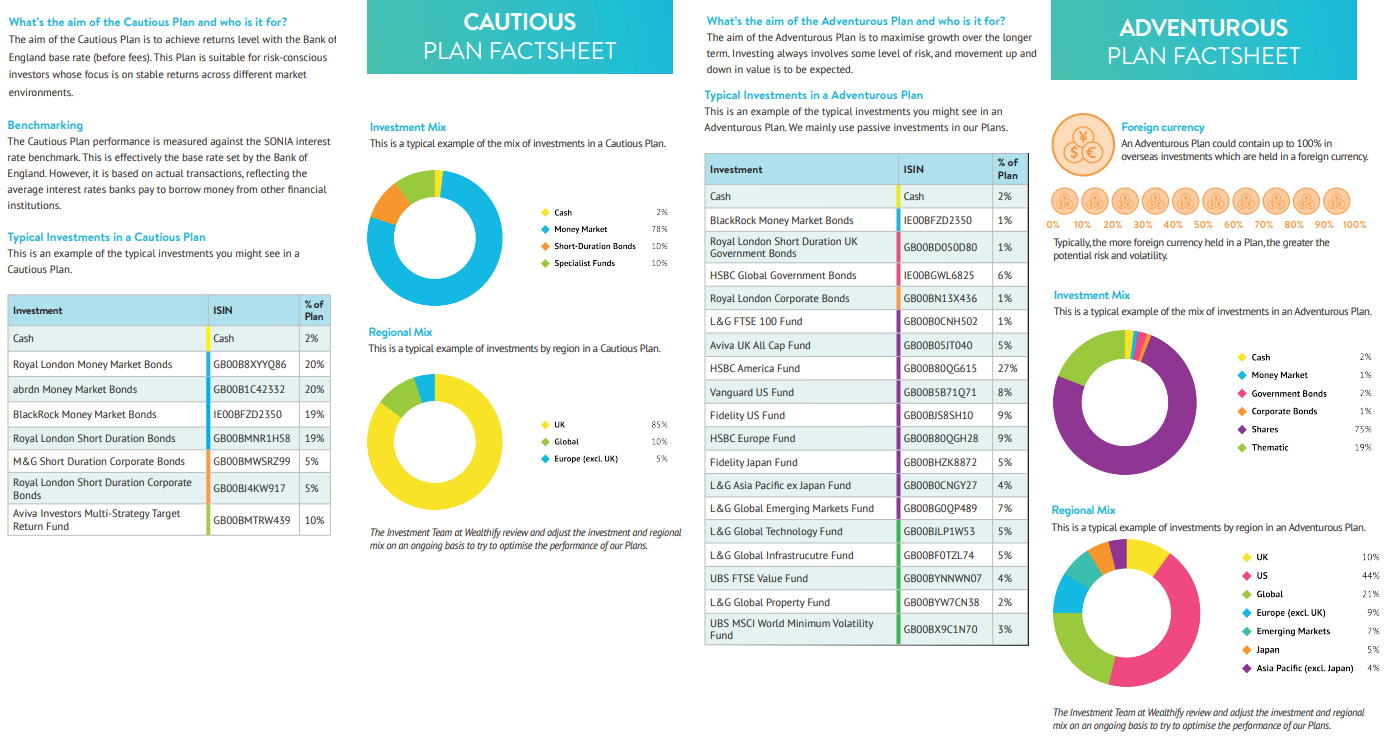
See full expert reviewOur verdictWealthify is a robo-advisor that lets you invest in a portfolio of investments from the UK and overseas or you can choose an ethical investment plan made from a blend of environmentally and socially responsible investments. Plus they are owned by Aviva. However, the high minimum deposit when opening an account may put smaller investors off. Capital at risk. Is Wealthify’s GIA a Good Investment Account?Pricing: It costs 0.6% to start investing with Wealthify, which is one of the cheapest robo-advisor GIA fees. There are also investment costs of, on average, 0.14% for original plans and 0.46% for ethical plans. Market Access: You can’t buy individual shares or ETFs with a Wealthify GIA, so it’s great for people that just want a basic fund to invest in on a regular basis. You can choose from the original or ethical plans and then set how much risk you want to take. Basically the more risk you take the more stocks (instead of bonds are allocated to your portfolio). It’s a bit annoying that you can’t see easy what each plan contains, but there are fact sheet details tucked away in the FAQs. But essentially, if you want better returns and are prepared to take on more risk it’s about 75% stocks in the adventurious original plan. If you are a cautious investors about 80% of your money is in money market funds (income generating investments) and cash. You can see the breakdown of the portfolios below as of 25/2/26.
App & Platform: Very easy to use on both app and desktop. Wealthify’s investment platform lets you fine-tune your portfolio based on risk, and shows you good visuals of what it may be worth in the future. The user interface is slick, offering you options for setting investment amounts, monthly investment amount and your investment style. Customer Service: Great customer service from real people based in Wales. Research & Analysis: Not really much analysis from Wealthify, but then again if you are a set-and-forget investor you don’t really need it as the investment team at Wealthify regularly update the plans and portfolios to ensure they are balanced and risk-appropriate. There are some quite funny YouTube videos that explain the market, and the odd instagram post with market updates. Is your money safe with Wealthify? Yes, as with all general investment accounts are authorised by the Financial Conduct Authority (FCA), if Wealthify were to go bust, your funds would be protected by the Financial Services Compensation Scheme (FSCS) up to £85,000. However, your money is not safe from the plans going down, with investing there is always a risk, but without risk there is no reward. Customer reviews for WealthifyCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.4.6Excellent Based on 2,571 reviews
Read customer reviewsAccessibleProcesses are easy to understand and staff are helpful and friendly. App is well designed and tell you what you need to know without data overload. I’m in control of my money without needing to be a financial expert EfficientCustomer service with Wealthify is second to none, whenever there’s an issue be it app based or user error, there’s always be a form of communication open to work out the problem. TrustworthyThey make me feel safe with my money in their hands VarietyGood selection of products made simple. SlickEasy to use platform, functional with handy and topical news ClarityProviding clear information and updates Steady Wealth ManagementGood steady return Good performanceProvides good performance, for 3 JISAs I hold for my three grandchildren. They’d get 5 stars if it wasn’t for the ludicrous 6-working-days waiting time before investments I make actually get credited to my grandchildren’s JISAs. In this day and age, that’s unacceptable, frankly. Easy way to start investingCan start with very small amounts. Very easy to use and professional Great company for all round saving and investingI’ve had an ISA, Pension and two Junior ISAs with Wealthify, and now more recently I’ve started saving with them too. Their platform is so simple to use and easy to understand. I feel like my money has grown so much more than it would have in a savings account, and I was lucky that I transferred my pension to them when I did, since it was out of the market (in the middle of being transferred from one provider to the other when markets fell) so my pension pot has only ever grown since. |
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees £0 |
Dealing Commission 0.05% |
See Offer Capital at risk |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.5.0Excellent Our experts have rated Interactive Brokers General Investment Account across one key area of our review framework.
Pros
Cons
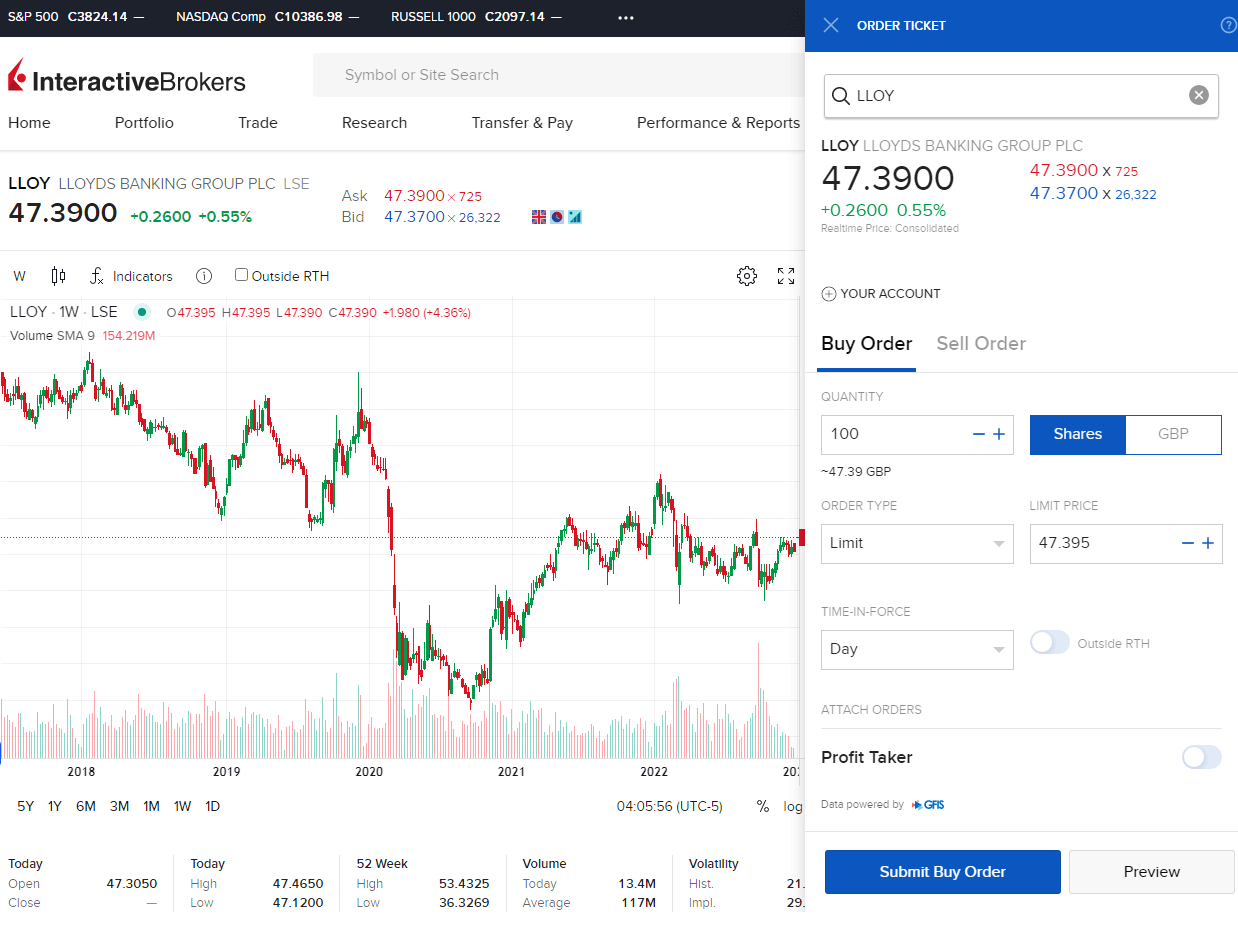
See full expert reviewOur verdictInteractive Brokers’ (IBKR’s) GIA is aimed at sophisticated investors, and offers access to derivatives, options, and futures. The platform is one of the cheapest across all asset classes. Capital is at risk. Is IBKR's GIA a Good Account?IBKR’s GIA is its “universal account” that lets you invest in all asset classes via shares, CFDs, futures, options or funds. The account is excellent for sophisticated investors who want to manage their own portfolios with complex order types. It’s ideal for active investors who need access to a wider range of investment products like derivatives, options, and futures. IBKR is also one of the cheapest investment platforms across all asset classes, as it was built on offering electronic discount brokerage. Fees There is no account charge for general investment accounts at IBKR. When you buy and sell shares minimum dealing commissions are £1 in the UK or 0.05% of the deal size. Special Offers IBKR clients can earn $200 for each qualified referral while giving their friend the opportunity to earn up to $1000 of IBKR stock. What is IBKR’s Platform Like to Use? The investment platform is a slimmed-down version of its exceptional desktop trader station. For investing it gives you a good overview of shares and funds.
|
||
 |
GMG Rating |
Customer Reviews |
GIA Annual Fees £0 |
Dealing Commission £0 |
See Offer Capital at risk |
Features:
|

Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
See full expert reviewOur verdictVerdict: Trading 212 offers commission-free access to over 13,000 stocks and ETFs. There is a Stocks ISA and a SIPP available for investors while those looking to save can access a Cash ISA. Trading 212 is a low-cost investment platform that offers access to stocks, ETFs, contracts for difference (CFDs), and more. Founded in 2004, it launched in the UK in 2013. Today, it has five million funded accounts globally and around £25 billion in client assets. Since 2016, its app has been the UK’s number one trading app. What does Trading 212 offer?– Special Offer: Deposit £1 & receive a free fractional share worth up to £100. Capital at risk. Sponsored link. T&Cs apply. – Cash ISA Bonus Rate: 4.61%. 3.6% variable + 1yr 1.01% bonus. Sponsored link. T&Cs apply. Trading 212 offers access to a broad range of stocks and ETFs across 16 exchanges. In total, there are over 13,000 stocks and ETFs available on the platform. Additionally, it offers access to a range of features that many traditional investment platforms don’t offer such as:
What accounts are available on Trading 212? Trading 212 currently offers a range of investment accounts including a regular investment account, a Stocks ISA, a Cash ISA, and a SIPP. We look at some of these accounts in more detail below. Stocks ISA With Trading 212’s Stocks ISA, you can invest in a broad range of stocks and ETFs commission-free, although other fees may apply. You can deposit up to £20,000 per year and there is no tax payable on investment gains or income but note, tax treatment depends on your individual circumstances and regulations which may change. Benefits of this account include:
Overall, the Trading 212 Stocks ISA is a solid offering. It could be a good option for those looking to trade stocks and ETFs with no commissions. Cash ISA The Trading 212 Cash ISA offers a simple way to save money. You can deposit up to £20,000 per year and withdraw your money at any time. Benefits of this account include:
This ISA could be well suited to those who want a Cash ISA on the same platform as their investments. It may be possible to find higher interest rates elsewhere, however. SIPP Trading 212’s SIPP is a pension account. With this product, you can deposit up to £60,000 every year, however, you cannot access the money until age 55 (57 from 2028). Trading 212’s SIPP is operated and administered by Platform One. Benefits of this account include:
Overall, this is a solid pension offering. There’s access to many investments and fees are very low. Market access Trading 212 offers access to UK stocks, international stocks, ETFs, investment trusts, and more. In total, there are over 13,000 global stocks and ETFs available on the platform which for most investors, is going to be more than enough options. Those in the UK can also access CFDs. With CFDs, it’s possible to trade indices, commodities, forex, and stocks. Where the platform falls short against traditional platforms, however, is mutual funds. Regular mutual funds are not available – only ETFs and investment trusts. One other thing to point out is that the company executes through Interactive Brokers. It can take time to fill orders on small UK stocks. What are Trading 212’s fees Trading 212’s fees are very competitive. Here’s a snapshot of its fee structure:
Note when buying UK shares, you still have to pay Stamp Duty. This is 0.5% of the transaction value. How does Trading 212 make money? Trading 212 offers commission-free trading and also charges no custody fees. So, how does it make money? Well, one source of revenue is CFDs – here it makes money from the spread, which is the difference between the buy and sell price of a CFD. Another source of revenue is interest on uninvested cash. Who is Trading 212 regulated by and is it safe? In the UK, Trading 212 is authorised and regulated by the Financial Conduct Authority (FCA). In the unlikely event of a default, FSCS compensation is up to £120,000. With Trading 212, your cash is held at some of the world’s largest banks where it is ring-fenced. This means that it is held separately to the firm’s money. As for shares, Trading 212 works with The Bank of New York Mellon and IBKR to safeguard your assets. Here, shares are ring-fenced and completely segregated from the company’s assets. So overall, the platform operates within safeguarding requirements. There are obviously risks that come with investing on the platform, however, especially if trading CFDs. App and platform Trading 212 offers desktop access and an app. The app, which has a 4.7 rating in Apple’s App Store – tends to be more popular with customers. Through the app, you can trade stocks and ETFs, check your account balances, analyse your portfolio and asset allocation, and research individual companies and ETFs. The interface is clean and suitable for both beginners and advanced investors. One issue to be aware of, however, is that the company is constantly tweaking the app and desktop interfaces. Some users find this frustrating. Added value and research Trading 212 offers more investing information than a lot of other low-cost platforms. On its ‘Learn’ page, there are many educational articles. That said, some topics are not explained that well. As a result, beginner investors could end up a little confused. One handy feature on the platform is the Trading 212 Hotlist. This shows the most popular stocks among its customers. On the downside, there doesn’t seem to be any investment research on the platform. The only source of investment ideas is the Hotlist. Customer service You can contact Trading 212 24/7 via the ‘contact us’ function in the app. This connects you with the T212 chat assistant who can connect you with an agent from the customer care team on chat. It should be noted, however, that some users have complained about poor customer service. One common theme is withdrawals, these seem to be an issue for many users. Please note, when investing, your capital is at risk and you may get back less than invested. Past performance is no guarantee of future results. Customer reviewsCustomer ratings come from reviews left on this site. Every review is read and approved before it is published.3.0Basic Based on 2 reviews
Read customer reviewsCustomer Service is non existentI would not recommend this app. I wasn’t able to give less than one star. I changed my phone and was asked verify my account again. This proved impossible and I am continually asked to upload my passport and photo. I’ve not been able to access my account for three weeks. Customer service is appalling – bots responding to you! I’ve now messaged and asked them to return my money and close my account. Lesson learned – I’ll stick with Aviva – at least you can speak to a human! Simple, intuitive, safeI started with a small amount with a growth and dividend strategy. I am now gaining over 10 percent growth and dividend reinvestment yearly. It is easy to use and although there is potential to lose. The new ai features and managed pies make it easy to start investing. Highly recommended. You can use my invite code for free shares, minimal investment. Leave a review |


Richard is the founder of the Good Money Guide (formerly Good Broker Guide), one of the original investment comparison sites established in 2015. With a career spanning two decades as a broker, he brings extensive expertise and knowledge to the financial landscape.
Having worked as a broker at Investors Intelligence and a multi-asset derivatives broker at MF Global (Man Financial), Richard has acquired substantial experience in the industry. His career began as a private client stockbroker at Walker Crips and Phillip Securities (now King and Shaxson), following internships on the NYMEX oil trading floor in New York and London IPE in 2001 and 2000.
Richard’s contributions and expertise have been recognized by respected publications such as The Sunday Times, BusinessInsider, Yahoo Finance, BusinessNews.org.uk, Master Investor, Wealth Briefing, iNews, and The FT, among many others.
Under Richard’s leadership, the Good Money Guide has evolved into a valuable destination for comprehensive information and expert guidance, specialising in trading, investment, and currency exchange. His commitment to delivering high-quality insights has solidified the Good Money Guide’s standing as a well-respected resource for both customers and industry colleagues.
Comments are closed.