Scanning the Financial Times recently, one particular quote stood out:
“The software sector,” warned Christian Hoffman of Thornburg Investment “is facing an existential crisis right now.”
“Both private credit and software,” he added, “are facing significant pullbacks.”[1]
Indeed. Deep corrections are noted in many famous IT/analytics stocks, such as SAP, RELX, Salesforce, Moody’s, Microsoft and Adobe. A wide swathe of companies are being hammered relentlessly.
This bout of ‘creative destruction’ is wrecking investment portfolios.
But then, I remember Buffett’s immortal quote: Be greedy when others are fearful. Are these intense ‘indiscriminate selling’ wildly overdone?
So the first question I ask is this: Will all these software companies go bust? I suspect not.
Many are using state-of-the-art AI tools in their businesses. They will continue to sell proprietary tools and analytic insights.
The second question: Will AI hit every company with the same impact? Again, I suspect not.
The evolving AI will change different sectors differently. Some will adapt and prosper; some will, inevitably, shrink.
The key is re-allocating capital to those companies that are using AI to improve their underlying businesses (that is, AI-induced productivity gain).
Since 2009, when the current bull market started, we have been witnessing a series of ‘rolling boom-bust’ sequences. Netflix, Tesla, Applovin, Palantir, for example, all experienced sharp rallies and decline at some point during the 17-year bull run.
The software sector’s recent decline is no different.
An oversold rebound may happen in the near term. Look at the iShares Software ETF (IGV). Prices have declined near its previous reaction low, where short-term buyers may enter to force a rebound.

At this point, perhaps investors should play to their edge. If a company’s stock decline is grossly overdone (than justified by its fundamentals), use the recent price decline to stack up. Knowing the backdrop of a company helps enormously.
If a company is underperforming the market and sector persistently, moving on may be the best tactic.
[1] https://www.ft.com/content/2c373617-123b-4c10-9acd-6ea929887a8a (paywall)
How To Buy Tech Stocks In The UK
To invest in tech stocks in the UK, you need a share dealing platform like Interactive Brokers, IG or AJ Bell.
| Name | Logo | GMG Rating | Customer Reviews | Annual Fees | Dealing Commission | CTA | Tag | Feature | Expand |
|---|---|---|---|---|---|---|---|---|---|
 |
GMG Rating |
Customer Reviews |
Annual Fees £0 |
Dealing Commission £0 |
See Offers Capital at risk
IG Reviews |
Featured |
Features:
|
Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
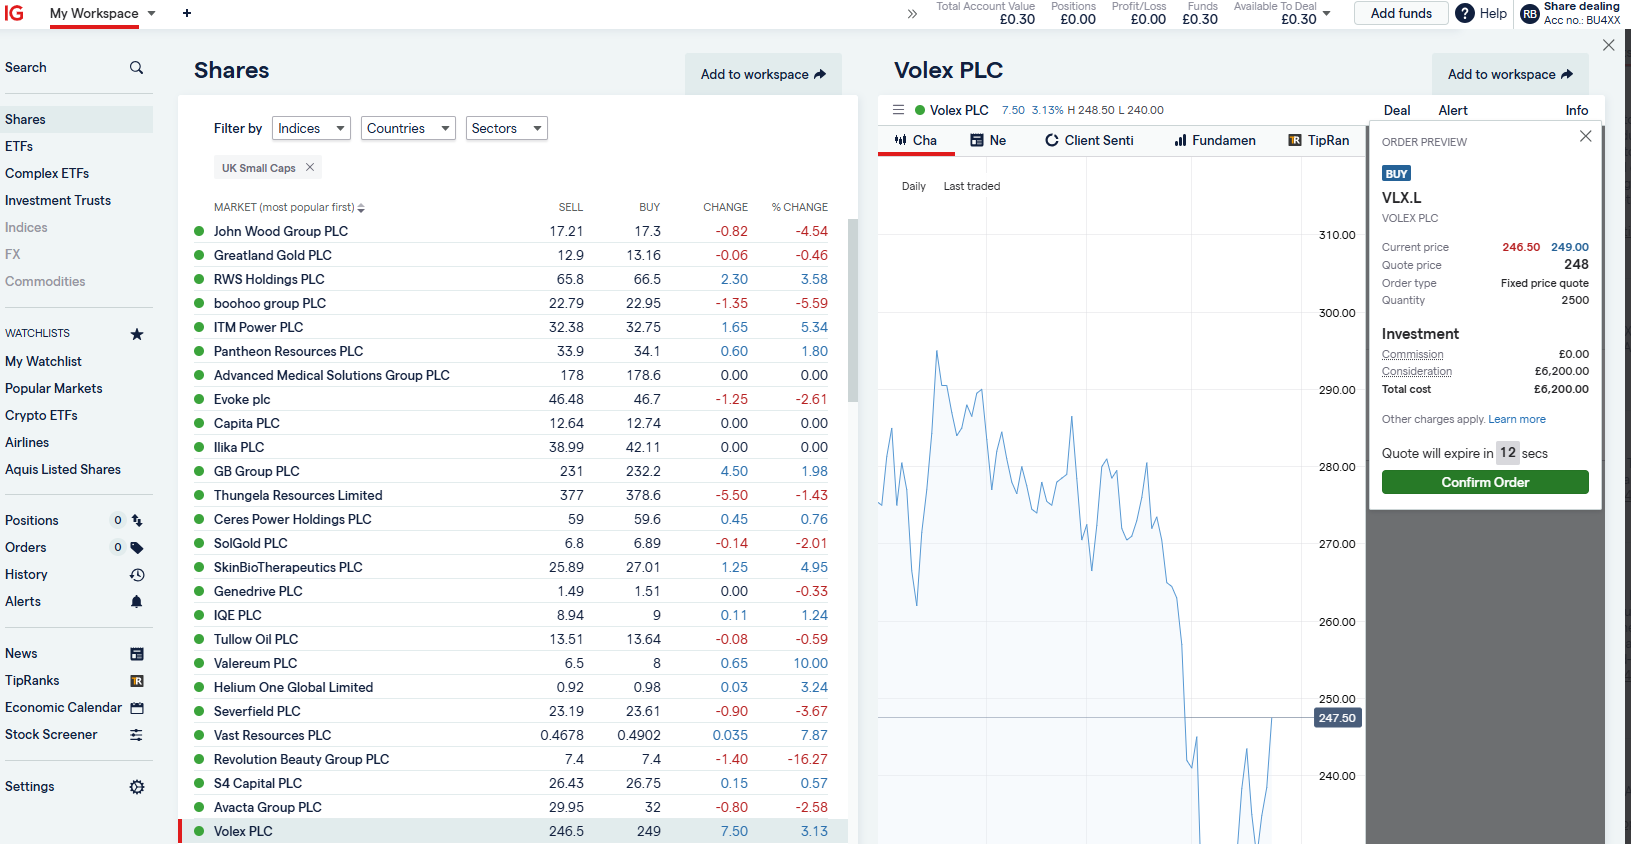
See full expert reviewOur verdictWith IG you can deal in over 13,000+ shares, funds and investment trusts with zero commission on US stocks and UK shares, with a foreign exchange fee of just 0.5%. You can also deal on a limited amount US shares while the market is closed. Is an IG share dealing account any good?An excellent share-dealing platform for those who want to deal shares regularly in the short and long term. You also get access to a huge range of UK small-cap shares, where you can request quotes from marketmakers via RSPs. This is something that is not available from other trading/investing platforms like CMC or Trading 212. An IG share dealing account is different from a spread betting or CFD trading account in that you actually own physical shares as opposed to trading derivatives. The ability to deal in shares with IG means that you can invest in companies for the long term alongside your short-term higher-risk speculation. An excellent share-dealing platform for those who want to deal in shares regularly in the short and long term.
|
|
 |
GMG Rating |
Customer Reviews |
Annual Fees 0% - 0.25% |
Dealing Commission £3.50 - £5 |
See Offers Capital at risk
AJ Bell Reviews |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Annual Fees 0% - 0.45% |
Dealing Commission £5.95 - £11.95 |
See Offers Capital at risk
Hargreaves Lansdown Reviews |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Annual Fees £0 |
Dealing Commission £3 |
See Offers Capital at risk
Interactive Brokers Reviews |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Annual Fees £59.88 |
Dealing Commission £3.99 |
See Offers Capital at risk
interactive investor Reviews |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Annual Fees £0 |
Dealing Commission £0 |
See Offers Capital at risk |
Features:
|
|
Jackson is a core part of the editorial team at GoodMoneyGuide.com.
With over 15 years of industry experience as a financial analyst, he brings a wealth of knowledge and expertise to our content and readers.
Previously, Jackson was the director of Stockcube Research as Head of Investors Intelligence. This pivotal role involved providing market timing advice and research to some of the world’s largest institutions and hedge funds.
Jackson brings a huge amount of expertise in areas as diverse as global macroeconomic investment strategy, statistical backtesting, asset allocation, and cross-asset research.
Jackson has a PhD in Finance from Durham University and has authored over 200 guides for GoodMoneyGuide.com.