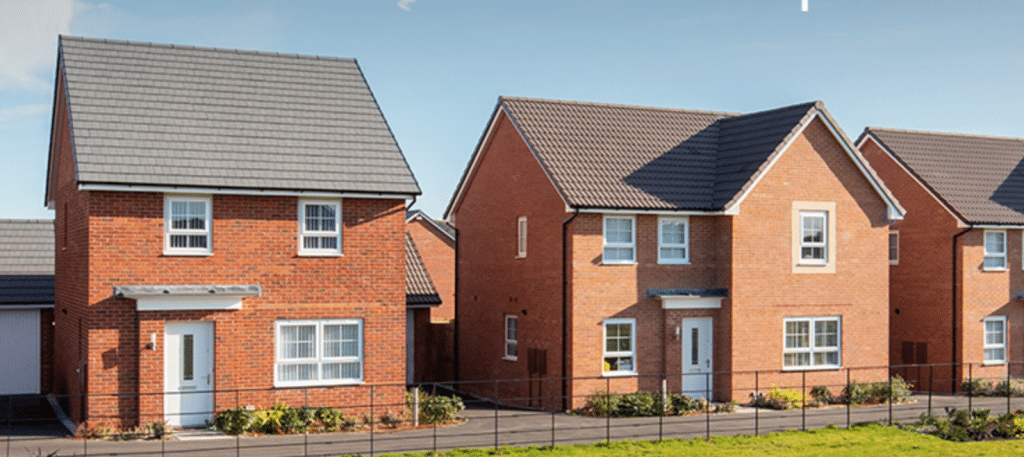
The government’s proposed Your First Home scheme may encourage developers to build more properties aimed at first-time buyers, but it is unlikely to produce a dramatic increase in overall housebuilding, according to Richard Dana, founder and CEO of mortgage specialist Tembo.
The scheme would allow eligible first-time buyers in England to purchase newly built homes with deposits as small as 2.5%, supported by a government-backed equity loan worth 20% of the property price.
The intention is to make homeownership more accessible while stimulating demand for newly constructed properties.
However, speaking at an industry breakfast attended by Good Money Guide, Dana questioned whether increasing demand for new-build homes would necessarily translate into substantially more houses being built.
He was responding to a journalist who highlighted expectations that developers such as Bellway could increase output by around 10% following the introduction of the scheme.
Dana suggested developers might instead change the mix of properties they build, moving away from larger homes aimed at existing homeowners and towards smaller properties more suitable for first-time buyers.
This could increase the number of individual homes completed without necessarily producing a comparable increase in the overall scale of development.
He also argued that housebuilders continued to face substantial obstacles, including planning delays, legal challenges and economic uncertainty.
Tembo’s First-Time Buyer Index Q3 2026 raises another concern: government support could increase demand for new-build properties without making them genuinely more affordable.
The research found that new-build homes cost more than existing properties in 10 of the 17 English cities analysed.
Across all 17 cities, the average new-build first-time buyer property cost £236,750, compared with £226,941 for an existing property.
This represents a premium of around £9,800, or 4.3%.
Dana argued that government-backed demand could encourage developers to maintain higher prices, potentially reducing the financial benefits intended for first-time buyers.
He was also sceptical about the historical evidence that Help to Buy had significantly increased the number of first-time buyers.
During the breakfast discussion, Dana said that annual first-time buyer numbers had actually been higher in recent years than during much of the period when Help to Buy was operating.
He suggested that the relationship between government-backed purchasing schemes and overall first-time buyer activity was therefore less straightforward than often assumed.
Another obstacle is mortgage affordability.
Tembo’s research found that in 13 of the 17 cities analysed, lower-income buyers would still need mortgages exceeding 4.5 times their annual household income, even with support from Your First Home.
That means the scheme could increase the number of people able to save the required deposit without necessarily increasing the number who can obtain a mortgage.
The report also found that 47% of the cities analysed would require median-income buyers to borrow more than 4.5 times their income.
Dana argued that the government should consider whether public money would be better spent tackling affordability problems rather than directing additional demand towards new-build developments.
He also questioned whether the government’s wider housebuilding ambitions were achievable without addressing the structural problems that restrict supply.
The distinction is important. A scheme that helps developers sell more properties is not necessarily one that results in substantially more homes being built.
For Your First Home to have a lasting impact on the housing market, it may need to be accompanied by planning reform, improved mortgage affordability and measures that ensure government assistance does not simply translate into higher property prices.
Richard is the founder of the Good Money Guide (formerly Good Broker Guide), one of the original investment comparison sites established in 2015. With a career spanning two decades as a broker, he brings extensive expertise and knowledge to the financial landscape.
Having worked as a broker at Investors Intelligence and a multi-asset derivatives broker at MF Global (Man Financial), Richard has acquired substantial experience in the industry. His career began as a private client stockbroker at Walker Crips and Phillip Securities (now King and Shaxson), following internships on the NYMEX oil trading floor in New York and London IPE in 2001 and 2000.
Richard’s contributions and expertise have been recognized by respected publications such as The Sunday Times, BusinessInsider, Yahoo Finance, BusinessNews.org.uk, Master Investor, Wealth Briefing, iNews, and The FT, among many others.
Under Richard’s leadership, the Good Money Guide has evolved into a valuable destination for comprehensive information and expert guidance, specialising in trading, investment, and currency exchange. His commitment to delivering high-quality insights has solidified the Good Money Guide’s standing as a well-respected resource for both customers and industry colleagues.