Buying a home with a mortgage remains financially better than renting across much of the UK, with first-time buyers potentially saving around £55,000 over five years compared with tenants, according to new research from mortgage and savings specialist Tembo.
However, the company’s latest First-Time Buyer Index for Q3 2026 reveals significant regional differences, with London emerging as one of the few places where renting can actually work out cheaper than buying.
The research compares the financial outcomes of renting and buying, taking into account mortgage interest, house price movements, rental costs, stamp duty and the potential investment returns available to renters who invest their deposit in the stock market instead.
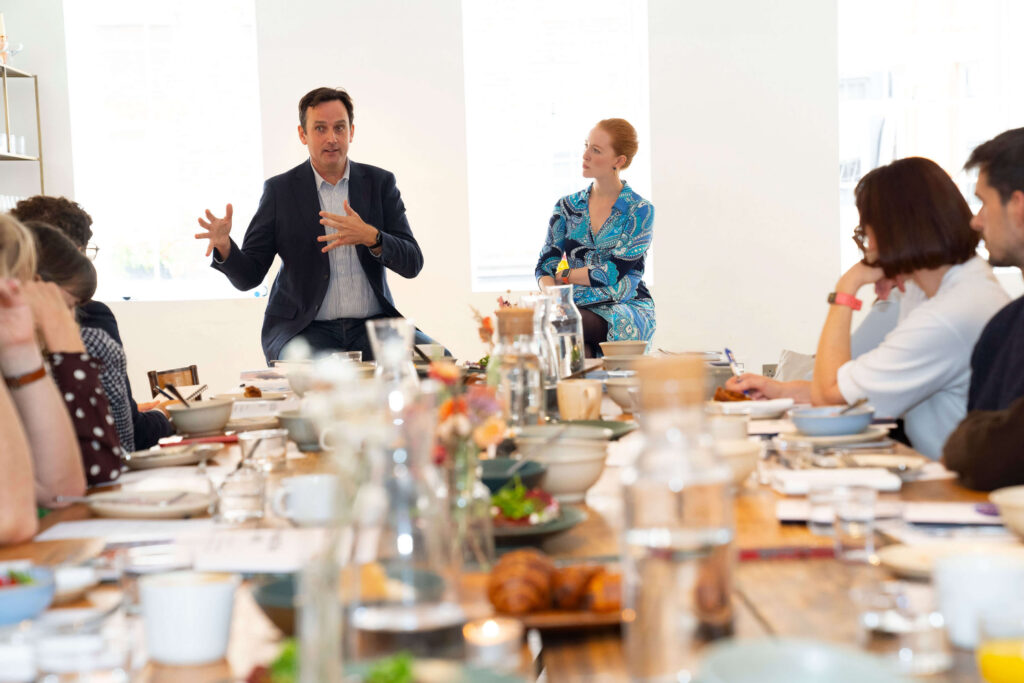
Speaking at an industry breakfast attended by Good Money Guide, Tembo founder and CEO Richard Dana explained that the research was designed to answer the question customers ask most frequently: is now a good time to buy a home?
Dana said that even after a prolonged period of relatively weak house price growth and strong stock market returns, buying still comes out ahead financially in many parts of the country.
But he stressed that the decision should not be based purely on potential financial returns. Buyers need to consider how long they intend to stay in a property, their job security and whether homeownership suits their lifestyle.
Glasgow topped Tembo’s ranking of 21 major UK cities for first-time buyers for the third consecutive quarter, followed by Belfast and Liverpool.
London came last, behind Brighton and Leicester.
The research found that buying in Bristol offered the biggest financial advantage over renting, at almost £111,000 over five years. Glasgow was close behind, with buyers potentially benefiting by more than £102,000 compared with renters.
By contrast, London has experienced a prolonged period of weak property price growth, making the financial case for buying considerably less compelling.
Dana said London could nevertheless represent an opportunity for buyers prepared to negotiate aggressively.
He explained that many sellers were still holding on to valuations established during the stronger property market of 2021, creating a substantial gap between asking prices and what buyers were prepared to pay.
First-time buyers, who do not have an existing property to sell, could be particularly well placed to take advantage.
The wider affordability picture remains challenging. Tembo’s Q3 index found that the average first-time buyer was now 34 years old, with a gross household income of £61,377 and a deposit of approximately £46,000.
The average first-time buyer property price had risen to £273,217, while the average monthly mortgage payment stood at £982.
Dana said the increase in the average age and income of buyers suggested that the housing market was becoming increasingly divided between more affluent households able to purchase property and lower-income households struggling to get started.
Ultimately, Tembo’s findings suggest that buying a home remains an effective way to build long-term wealth, but it is no longer automatically the best financial decision in every city.
For prospective buyers, the most important considerations may be how long they plan to remain in the property, whether they can comfortably afford the mortgage and whether they are buying at a sensible price.
Richard is the founder of the Good Money Guide (formerly Good Broker Guide), one of the original investment comparison sites established in 2015. With a career spanning two decades as a broker, he brings extensive expertise and knowledge to the financial landscape.
Having worked as a broker at Investors Intelligence and a multi-asset derivatives broker at MF Global (Man Financial), Richard has acquired substantial experience in the industry. His career began as a private client stockbroker at Walker Crips and Phillip Securities (now King and Shaxson), following internships on the NYMEX oil trading floor in New York and London IPE in 2001 and 2000.
Richard’s contributions and expertise have been recognized by respected publications such as The Sunday Times, BusinessInsider, Yahoo Finance, BusinessNews.org.uk, Master Investor, Wealth Briefing, iNews, and The FT, among many others.
Under Richard’s leadership, the Good Money Guide has evolved into a valuable destination for comprehensive information and expert guidance, specialising in trading, investment, and currency exchange. His commitment to delivering high-quality insights has solidified the Good Money Guide’s standing as a well-respected resource for both customers and industry colleagues.