Yes, we rate Wealthify as a good pension provider, as they offer ready-made portfolios and are owned by Aviva, but there are some downsides. Read our full Wealthify pension review to see if they are right for you.
- Experts commend Wealthify Pension for its competitive management fees, particularly for SIPP accounts over £100,000, which have been reduced to 0.3%. They highlight the platform's ease of use and strong customer service, while noting the limitation of not allowing individual share investments.
- Across 2571 user reviews on Good Money Guide, averaging 4.6/5, customers frequently praise the user-friendly platform and the clarity of information provided. Many appreciate the efficient customer service and the ability to invest with low minimum amounts, although some express concerns about the waiting time for investment credits.
Wealthify Pension Expert rating
Our expert rating is the average of the areas listed here, each scored out of 5 by our team.- Pricing5.0
- Market Access4.5
- Online Platform5.0
- Customer Service5.0
- Research & Analysis4.5
Pros
- Managed pension
- Owned by Aviva
- Relatively low annual account fee
Cons
- Can't invest in individual shares
- £5,000 minimum deposit
See full expert review
Our verdict
Overall we rate Wealthify as a good managed pension as they won Best Private Pension Provider 2025 in the Good Money Guide Awards, but it is not a SIPP pension as you cannot invest in individual shares, instead you pick one of their portfolios based on how much risk you want to take, so it's more of a private managed personal pension. Wealthify is authorised and regulated by the Financial Conduct Authority and owned by Aviva.
Capital at risk. Your tax treatment will depend on your individual circumstances and it may be subject to change in the future.
Is Wealthify's pension any good?
Wealthify won "Best Pension" in the 2025 Good Money Guide Awards as it lets you invest either in an original portfolio of investments from the UK and overseas or choose an ethical investment plan made from a blend of environmentally and socially responsible investments.
Pension Fees: Wealthify has recently cut management fees for SIPP accounts holding more than £100,000 by introducing a tiered charging structure.
Any amount above £100,000 in Wealthify Personal Pension accounts will be charged at a lower annual fee of 0.3%, putting the service in a very competitive position against other providers.
This represents a reduction on the offering’s standard annual fee of 0.6% on balances up to £100,000. Both fees are charged monthly. In real terms, that means if you have £200,000 in your Welathify pension, your fees will now be £300 a year lower
The updated pricing structure is aimed at enhancing the appeal of Wealthify’s SIPP, particularly among more affluent clients.
Wealthify chief executive Richard Ambrose said: “Too many people are unaware of what they are paying in fees. It’s our duty as pension providers to make this clear. Fees are charged as a percentage of the pension pot, so the more you put in, the more fees will eat into your retirement savings.
“Whatever stage people are at with their pensions, I hope Wealthify’s new tiering inspires them to review their fees and vote with their feet so that they aren’t paying more than they need to.”
By introducing tiered fees, Aviva-owned Wealthify's SIPP offering comes in line with its direct digital wealth manager competitors Nutmeg and Moneyfarm, as well as other personal pension providers.
Moneyfarm for example have slightly higher tiered management fees depending on the amount of assets held in their SIPPs. Wealthify’s decision to cut its pension management fees on sums above £100,000 to 0.3% puts it in a more competitive position.
Its “Fixed Allocation” service carries a fee of 0.45% up to £100,000 and then 0.25% on further investments.
It is important to note that these charges concern only the management of the SIPP and do not account for other costs such as the fees of funds (average fund fees for Original portfolios are 0.14%, and for Ethical: 0.46%) in which portfolios are invested or transaction fees.
Market Access: You can only invest in either an Original Plan or an Ethical Plan with Wealthify, so you can't buy individual shares. So Wealthify's pension is better for those who just want to invest passively without being too involved. Once you have chosen your plan, you can then decide how much risk to take on by setting your pension from cautious to adventurous. You can see the difference in how Wealthify pensions are balanced for risk below, the more risk/reward you choose, the more stocks are allocated to your portfolio.
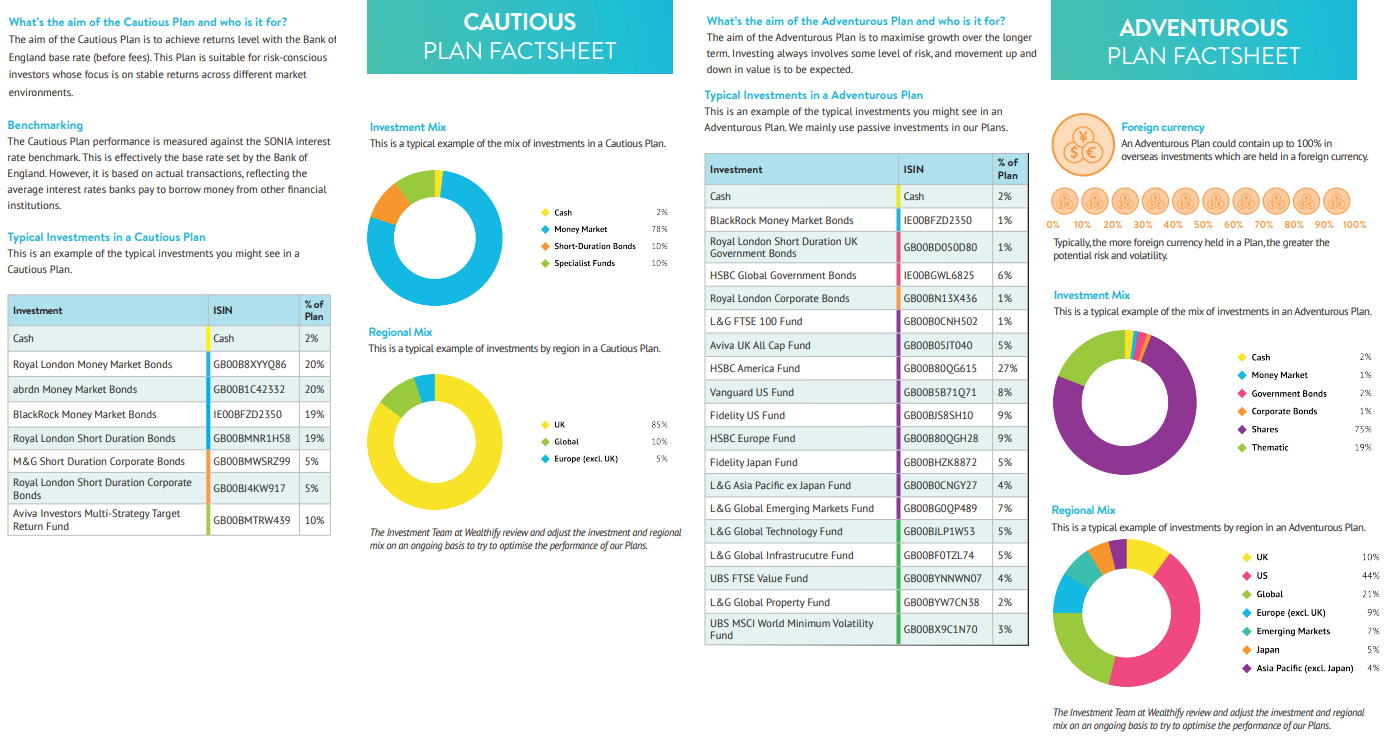
Wealthify screenshots taken Feb 2026
Performance: Excluding fees, Wealthify plans have returned just over 24% since 2019, with an average return of just over 4% per year. Which, if we're honest, is not great seeing as the S&P, the major US stock market that contains 500 of the biggest US public companies, has returned around 85%. It's not exactly a fair comparison because Wealthify plans are diversified (as portfolios are supposed to be) across bonds and different countries.
It will certainly be interesting to see the 2026 performance update after the most recent stock market crash, where you'd expect a diversified portfolio to be more resilient than an index tracker.
Customer Service: Great support from Wealthify from an experienced team that can help with any issues either via email, chat or over the phone.
App & platform: Both are easy to use and easy to navigate.
Research & Analysis: When you are logged in, you get some brief market updates online, but that's about it, other than the odd email, about how things like the budget may affect your investments.
Remember that past performance is not an indication of future results.
Capital at risk. Your tax treatment will depend on your individual circumstances and it may be subject to change in the future.
Customer reviews for Wealthify
Customer ratings come from reviews left on this site. Every review is read and approved before it is published.Based on 2,571 reviews
- Excellent68%
- Very good24%
- Basic6%
- Poor1%
- Bad1%
Read customer reviews
Makes investing easy!
Makes investing easy!
Highly recommend
Highly recommend
Really easy
Really easy
Great value simple investing
Great value simple investing
?
?
Excellent General Investment Plan
Excellent General Investment Plan
Surprised by information provided, product...
Surprised by information provided, product and industry related
Easy to use
Easy to use
Easy to use amm
Easy to use amm
Easy to invest and understand...
Easy to invest and understand with good communication
Good
Good
Competent
Competent
great app with good info
great app with good info
i dont know enough
i dont know enough
Outperformed by Moneyfarm for overall...
Outperformed by Moneyfarm for overall return
Okay
Okay
5/5
Easy to use and the...
Easy to use and the communications are good and easy to understand.
Low costs
Low costs
Low costs
Low costs
Wealthify Alternative Pension Providers
| Name | Logo | GMG Rating | Customer Reviews | Pension Fees | Minimum Deposit | CTA | Tag | Feature | Expand |
|---|---|---|---|---|---|---|---|---|---|
 |
GMG Rating |
Customer Reviews |
Pension Fees £210 |
Minimum Deposit £1 |
See Offer Capital at risk |
Featured |
Features:
|
|
|
 |
GMG Rating |
Customer Reviews |
Pension Fees £155.88 |
Minimum Deposit £1 |
See Offer Capital at risk |
Features:
|
interactive investor Pensions Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.5.0Excellent Our experts have rated interactive investor Pensions across five key areas of our review framework.
Pros
Cons
Our verdictInteractive Investor offers the most investment options in the UK SIPP markets. With II you can invest more than 40,000 domestic and international shares, ETFs, bonds and over 3,000 funds (AJ Bell has 2,000 and HL offers 2,500 funds). Is Interactive Investors' SIPP (pension) any good?Yes, interactive investor won "Best SIPP Provider" in the 2025 Good Money Guide Awards. ii has a really good pre-selected fund section, which makes crucial SIPP asset allocation decisions much easier. It's very low cost too, with excellent education and research, and a huge range of investments to choose from. The key advantage of interactive investor’s SIPP is that it has a flat-fee structure. This means that annual account charges do not increase as your pension pot grows in size. This structure can help those with larger SIPP portfolios save on fees, however it can be a little expensive for small pensions if you are just starting to invest for your retirement. For smaller pension pots, those that just want to invest in ETFs, InvestEngine offer a free SIPP, but it is limited to just UK-listed ETFs, so you can't buy individual shares. One of the good things about ii's SIPP is that you can buy bonds, gilts, and shares in small and large UK and international companies. Even though ii charges £3.99 for buying funds. If you compare this to Hargreaves Lansdown, which does not charge for buying and selling funds, but HL SIPP fees are higher. If you have £100,000 in your SIPP with ii you'd pay £71.88 a year, versus HL where your fees would be £450. So, if you have a big pension, is it worth moving it to ii? Well, yes at the moment, as interactive investor claim their SIPP pricing can give you an additional £68,467 towards your pension after 30 years compared to HL. Plus, if you transfer your SIPP to ii before 31st August, you can claim up to £2,000 in cash back.
Of course, you’ll need to add cash or start a transfer of a minimum value of £10,000 to qualify for your cashback reward. Terms apply. |
||
|
|
GMG Rating |
Customer Reviews |
Pension Fees 0.6% - 0.3% |
Minimum Deposit £5,000 |
See Offer Capital at risk |
Features:
|
Wealthify Pension Expert ratingOur expert rating is the average of the areas listed here, each scored out of 5 by our team.
Pros
Cons
Our verdictOverall we rate Wealthify as a good managed pension as they won Best Private Pension Provider 2025 in the Good Money Guide Awards, but it is not a SIPP pension as you cannot invest in individual shares, instead you pick one of their portfolios based on how much risk you want to take, so it's more of a private managed personal pension. Wealthify is authorised and regulated by the Financial Conduct Authority and owned by Aviva. Is Wealthify's pension any good?Wealthify won "Best Pension" in the 2025 Good Money Guide Awards as it lets you invest either in an original portfolio of investments from the UK and overseas or choose an ethical investment plan made from a blend of environmentally and socially responsible investments. Pension Fees: Wealthify has recently cut management fees for SIPP accounts holding more than £100,000 by introducing a tiered charging structure. Any amount above £100,000 in Wealthify Personal Pension accounts will be charged at a lower annual fee of 0.3%, putting the service in a very competitive position against other providers. This represents a reduction on the offering’s standard annual fee of 0.6% on balances up to £100,000. Both fees are charged monthly. In real terms, that means if you have £200,000 in your Welathify pension, your fees will now be £300 a year lower The updated pricing structure is aimed at enhancing the appeal of Wealthify’s SIPP, particularly among more affluent clients. Wealthify chief executive Richard Ambrose said: “Too many people are unaware of what they are paying in fees. It’s our duty as pension providers to make this clear. Fees are charged as a percentage of the pension pot, so the more you put in, the more fees will eat into your retirement savings. “Whatever stage people are at with their pensions, I hope Wealthify’s new tiering inspires them to review their fees and vote with their feet so that they aren’t paying more than they need to.” By introducing tiered fees, Aviva-owned Wealthify's SIPP offering comes in line with its direct digital wealth manager competitors Nutmeg and Moneyfarm, as well as other personal pension providers. Moneyfarm for example have slightly higher tiered management fees depending on the amount of assets held in their SIPPs. Wealthify’s decision to cut its pension management fees on sums above £100,000 to 0.3% puts it in a more competitive position. Its “Fixed Allocation” service carries a fee of 0.45% up to £100,000 and then 0.25% on further investments. It is important to note that these charges concern only the management of the SIPP and do not account for other costs such as the fees of funds (average fund fees for Original portfolios are 0.14%, and for Ethical: 0.46%) in which portfolios are invested or transaction fees. Market Access: You can only invest in either an Original Plan or an Ethical Plan with Wealthify, so you can't buy individual shares. So Wealthify's pension is better for those who just want to invest passively without being too involved. Once you have chosen your plan, you can then decide how much risk to take on by setting your pension from cautious to adventurous. You can see the difference in how Wealthify pensions are balanced for risk below, the more risk/reward you choose, the more stocks are allocated to your portfolio.
Wealthify screenshots taken Feb 2026 Performance: Excluding fees, Wealthify plans have returned just over 24% since 2019, with an average return of just over 4% per year. Which, if we're honest, is not great seeing as the S&P, the major US stock market that contains 500 of the biggest US public companies, has returned around 85%. It's not exactly a fair comparison because Wealthify plans are diversified (as portfolios are supposed to be) across bonds and different countries. It will certainly be interesting to see the 2026 performance update after the most recent stock market crash, where you'd expect a diversified portfolio to be more resilient than an index tracker. Customer Service: Great support from Wealthify from an experienced team that can help with any issues either via email, chat or over the phone. App & platform: Both are easy to use and easy to navigate. Research & Analysis: When you are logged in, you get some brief market updates online, but that's about it, other than the odd email, about how things like the budget may affect your investments. Remember that past performance is not an indication of future results. Capital at risk. Your tax treatment will depend on your individual circumstances and it may be subject to change in the future. |
||
 |
GMG Rating |
Customer Reviews |
Pension Fees 0.75% |
Minimum Deposit £1 |
See Offer Capital at risk |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Pension Fees 0% - 0.25% |
Minimum Deposit £500 |
See Offer Capital at risk |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Pension Fees 0.45% |
Minimum Deposit £100 |
See Offer Capital at risk |
Features:
|
|
||
 |
GMG Rating |
Customer Reviews |
Pension Fees 0% |
Minimum Deposit £1 |
See Offer Capital at risk |
Features:
|
|

Richard is the founder of the Good Money Guide (formerly Good Broker Guide), one of the original investment comparison sites established in 2015. With a career spanning two decades as a broker, he brings extensive expertise and knowledge to the financial landscape.
Having worked as a broker at Investors Intelligence and a multi-asset derivatives broker at MF Global (Man Financial), Richard has acquired substantial experience in the industry. His career began as a private client stockbroker at Walker Crips and Phillip Securities (now King and Shaxson), following internships on the NYMEX oil trading floor in New York and London IPE in 2001 and 2000.
Richard’s contributions and expertise have been recognized by respected publications such as The Sunday Times, BusinessInsider, Yahoo Finance, BusinessNews.org.uk, Master Investor, Wealth Briefing, iNews, and The FT, among many others.
Under Richard’s leadership, the Good Money Guide has evolved into a valuable destination for comprehensive information and expert guidance, specialising in trading, investment, and currency exchange. His commitment to delivering high-quality insights has solidified the Good Money Guide’s standing as a well-respected resource for both customers and industry colleagues.